Texas boasts a regionally and nationally competitive tax code. The state does not impose an individual income tax. However, unlike most others without an individual income tax, Texas (like Washington) applies the corporate gross receipts tax (also known as the “margin tax”) to S corporation and LLC income when others accord them pass-through status.
The margin tax is complex and burdensome. As a modified gross receipts tax, it applies to a firm’s total sales with limited deductions, rather than being imposed on profits.
In 2023, Texas voted to increase the homestead exemption on residential property from $40,000 to $100,000 ($110,000 for the elderly, disabled, and disabled veterans). This exemption is limited to school district property taxes alone, and the state replaces lost education funding with general fund revenue. Instead of shifting the tax burden directly to commercial property and renters like most homestead exemptions, this policy redirects the burden to the state’s general revenue sources, and thus to all taxpayers regardless of home ownership.
Texas treats remote sellers and marketplace facilitators competitively. Unlike most other states that require such sellers to collect and remit sales taxes if either a transaction or dollar threshold is surpassed, Texas only imposes a dollar threshold. Additionally, the dollar threshold is $500,000, greater than most other states, which better aligns the threshold with the size of the state’s economy.
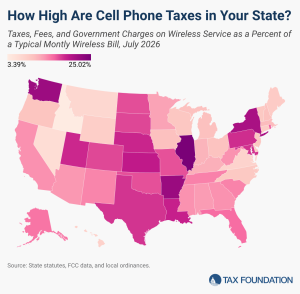
Applying the sales tax, a traditional broad-based consumption tax, is perfectly appropriate, but excessive targeted taxation of wireless services lacks the traditional justifications—a user-pays system or the internalization of social costs—for excise taxation, raising consumer costs and discouraging investment.
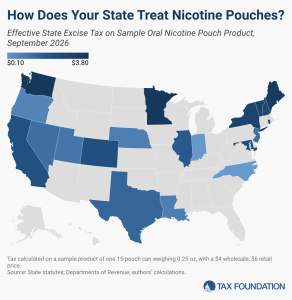
Oral nicotine pouches have rapidly become a popular option for consumers who want nicotine without the harmful combustion and chemicals of traditional cigarettes. As these alternative nicotine products (ANPs) successfully draw smokers to non-combustible nicotine consumption, many states have scrambled to incorporate these new products into their tax regimes.