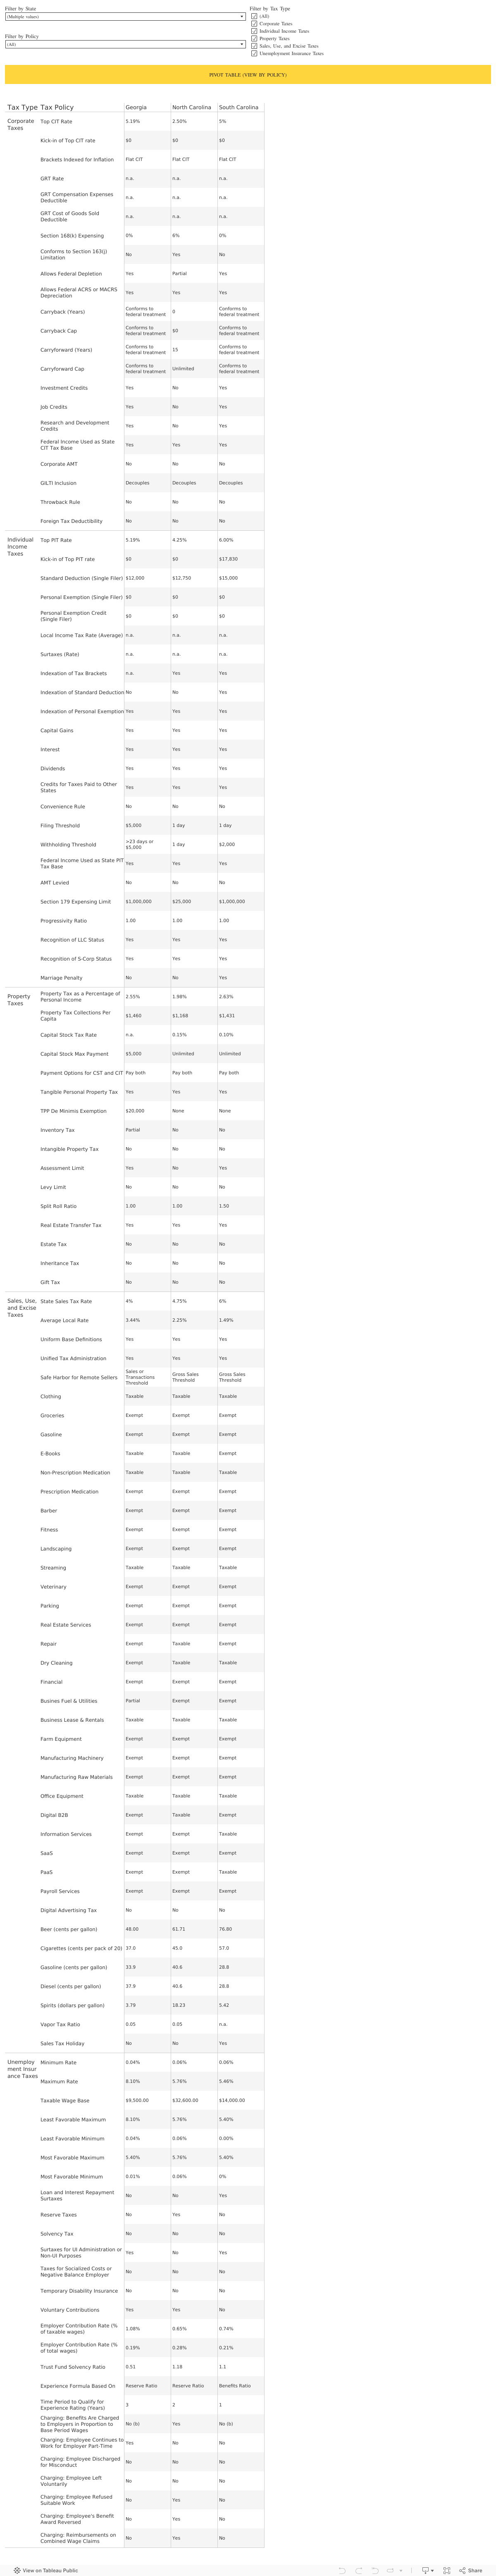
South Carolina levies an individual income tax with two brackets, a top marginal rate of 6 percent, and a marriage penalty. By contrast, neighboring North Carolina levies a flat individual income tax and does not impose a marriage penalty, making South Carolina’s levy particularly uncompetitive. Pass-through businesses enjoy a preferential rate on business income, which helps them but creates distortions and drives up the ordinary rate.
The Palmetto State maintains a reasonably competitive corporate tax code, featuring a flat rate of 5 percent. However, the state also relies unusually heavily on tax credits rather than focusing on broad-based rate relief. The state imposes a capital stock tax without capping maximum payments. Capital stock taxes are levied against a business’s net worth (or accumulated wealth) and tend to penalize investment. Moreover, businesses are required to pay capital stock taxes regardless of profitability.
The state also applies a different formula to assess distinct property types, known as split roll taxation, and South Carolina is the only state to apply school property taxes to commercial and industrial property but not to residential property, raising costs for businesses and renters compared to homeowners.
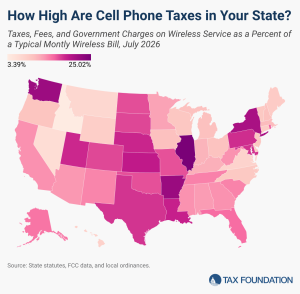
Applying the sales tax, a traditional broad-based consumption tax, is perfectly appropriate, but excessive targeted taxation of wireless services lacks the traditional justifications—a user-pays system or the internalization of social costs—for excise taxation, raising consumer costs and discouraging investment.
Privacy concerns are a primary driver of opposition to vehicle miles traveled (VMT) tax systems, but VMT taxes do not need to invade drivers’ privacy to efficiently fund the roads.