Vermont levies all major categories of taxation with comparatively high rates and an overall uncompetitive tax structure. As a result, the tax code makes the state both nationally and regionally uncompetitive, particularly compared to neighboring low-tax New Hampshire.
Vermont levies an individual income tax with multiple brackets, including a top marginal rate of 8.75 percent; the tax also includes a marriage penalty for joint filers. The Green Mountain State levies a tax at a flat rate of 16 percent on estates worth more than $5 million.
Property taxpayers in the state are subject to the highest effective rate of taxation as a percentage of personal income. Further, property tax collections per capita in the state are among the highest in the country ($3,178). The state’s sales tax base is unnecessarily narrow and exempts many personal goods and services while also subjecting many business inputs to the tax, which causes tax pyramiding and ultimately increases the costs borne by consumers.
The Vermont corporate tax features three brackets with a top marginal rate of 8.5 percent. Importantly, these brackets are not indexed for inflation, meaning taxpayers will be forced into a higher tax bracket when their nominal income increases, but due to inflation, their real income does not (or even declines). Net operating loss carryforwards are limited to 10 years, with no corresponding carryback allowance, and Vermont is among the minority of states that tax net CFC-tested income (NCTI).
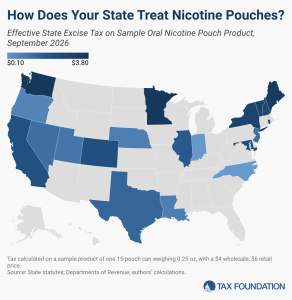
Oral nicotine pouches have rapidly become a popular option for consumers who want nicotine without the harmful combustion and chemicals of traditional cigarettes. As these alternative nicotine products (ANPs) successfully draw smokers to non-combustible nicotine consumption, many states have scrambled to incorporate these new products into their tax regimes.
Privacy concerns are a primary driver of opposition to vehicle miles traveled (VMT) tax systems, but VMT taxes do not need to invade drivers’ privacy to efficiently fund the roads.