New Jersey levies all major categories of tax, typically at high rates and significant levels of complexity.
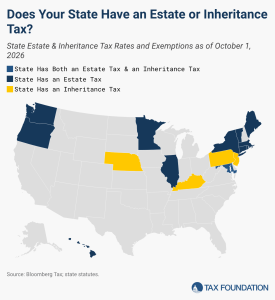
In 1976, the Garden State enacted an individual income tax, in part to provide relief from rising property taxes. Now, individual taxpayers are subject to seven individual income tax brackets, a top marginal rate of 10.75 percent, and among the highest per capita property tax collections in the nation. Moreover, individual taxpayers are subject to a marriage penalty. New Jersey property taxpayers also pay the third-highest effective rate in the country. The state repealed its estate tax but continues to levy an inheritance tax.
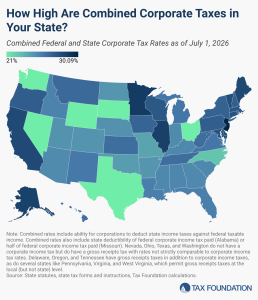
Corporations face a top marginal tax rate of 11.5 percent, taking into account a surtax on large businesses known as the Corporate Transit Fee. Recently, however, New Jersey has largely removed global intangible low-taxed income (GILTI) from its tax base, and tangible personal property is exempt from property taxation. Additionally, the state allows up to 20 years of net operating loss carryforwards without placing a cap on the dollar amount allowed.
Imposing sales taxes on rental car companies’ fleet purchases, in addition to the sales and rental car excise taxes levied when those cars are rented, yields double taxation and causes harmful tax pyramiding.
In addition to the federal estate tax, which has a top marginal rate of 40 percent, 12 states and the District of Columbia impose estate taxes, while five states levy inheritance taxes.
Corporations in the United States pay federal corporate income taxes levied at a 21 percent rate. Forty-four states and D.C. also levy taxes on corporate income, with top marginal rates ranging from 2.5 percent in North Carolina to 11.5 percent in New Jersey.