Missouri performs well overall on the Index, with top 10 rankings on the corporate tax and UI tax components, as well as a competitive ranking on the property tax component. The Show Me State achieves this by applying low rates to broad bases in its individual and corporate income taxes, despite permitting local income taxes, which marginally increase the burden on workers in localities that impose this tax.
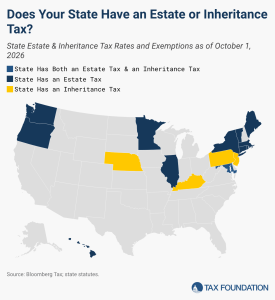
The state also avoids other harmful structural provisions such as a throwback rule, capital stock tax, inventory tax, gross receipts taxes, and estate or inheritance taxes.
Missouri’s weakest performance is on the sales tax component due to a high combined state and average local rate that is the result of Missouri’s average local rate being nearly as high as the statewide rate. Missouri’s sales tax score nevertheless ranks near the middle of the pack, helped by a uniform state and local sales tax base and Missouri’s avoidance of taxing many business inputs. Missouri, however, may find it hard to adapt its sales tax to a changing economy due to a voter-approved constitutional amendment restricting the broadening of the sales tax base.
Imposing sales taxes on rental car companies’ fleet purchases, in addition to the sales and rental car excise taxes levied when those cars are rented, yields double taxation and causes harmful tax pyramiding.
In addition to the federal estate tax, which has a top marginal rate of 40 percent, 12 states and the District of Columbia impose estate taxes, while five states levy inheritance taxes.
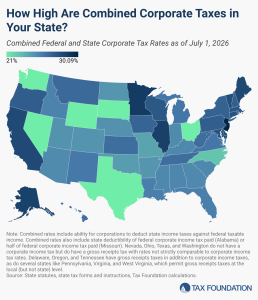
Corporations in the United States pay federal corporate income taxes levied at a 21 percent rate. Forty-four states and DC also levy taxes on corporate income, with top marginal rates ranging from 2.5 percent in North Carolina to 11.5 percent in New Jersey.