Rhode Island ranks relatively poorly overall due to below-average rankings on all five components. Hurting Rhode Island’s individual income tax component ranking is the sizeable marriage penalty in its individual income tax brackets, with bracket thresholds that are not adjusted for married couples. On the corporate component, Rhode Island taxes net CFC-tested income (NCTI), making it more expensive for corporations to do business in the Ocean State. Furthermore, Rhode Island does not offer bonus depreciation even though it conforms to the federal limitation on business net interest deductibility. However, Rhode Island recently made strides to improve its treatment of business net operating losses (NOLs) by increasing the NOL carryforward period from 5 to 20 years, bringing it more in line with other states.
On the property tax component, Rhode Island benefits from forgoing a capital stock tax and only partially taxing tangible personal property, but the state continues to levy an estate tax, taxes commercial property more heavily than residential property, and collects relatively high property taxes per capita and as a share of owner-occupied housing value.
While Rhode Island’s state sales tax rate is among the highest in the country, its lack of local sales taxes places the combined state and average local sales tax rate near the middle of the pack. Notably, however, Rhode Island has one of the highest tobacco tax rates in the country. Furthermore, despite recent reforms, Rhode Island’s UI tax continues to rank among the least competitive in the country due to high minimum and maximum rates, a wage base that exceeds the federal wage base, a long experience rating qualifying period, and a surtax.
Imposing sales taxes on rental car companies’ fleet purchases, in addition to the sales and rental car excise taxes levied when those cars are rented, yields double taxation and causes harmful tax pyramiding.
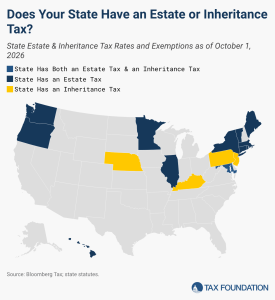
In addition to the federal estate tax, which has a top marginal rate of 40 percent, 12 states and the District of Columbia impose estate taxes, while five states levy inheritance taxes.
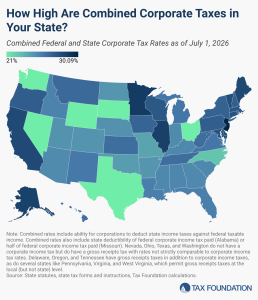
Corporations in the United States pay federal corporate income taxes levied at a 21 percent rate. Forty-four states and D.C. also levy taxes on corporate income, with top marginal rates ranging from 2.5 percent in North Carolina to 11.5 percent in New Jersey.