Oregon forgoes a sales tax but doubles down on other forms of taxation. The state has a complex and progressive individual income tax system with four tax brackets, a top marginal rate of 9.9 percent, and a personal exemption structured as a tax credit. Additionally, the tax brackets are not adjusted for inflation. Portland has the highest combined local income tax rate in the nation (4 percent), adding an extra layer of tax burden for residents of the state’s largest city.
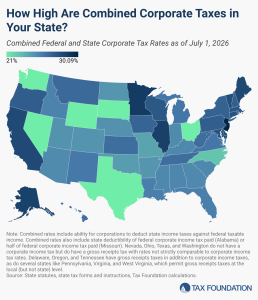
The absence of a sales tax in Oregon is offset by an overly complex corporate tax system, which includes a 7.6 percent corporate income tax, a 0.57 percent gross receipts tax (the Corporate Activity Tax), and additional corporate taxes at the local level, particularly in the Portland area. Although gross receipts taxes typically do not allow any deductions from gross sales, the CAT provides a 35 percent deduction for either labor costs or the cost of goods sold. However, this does not significantly improve Oregon’s competitiveness in attracting businesses, as the state’s corporate tax system ranks among the worst in the nation, comparable to Delaware, the only other state to combine corporate income and gross receipts taxes.
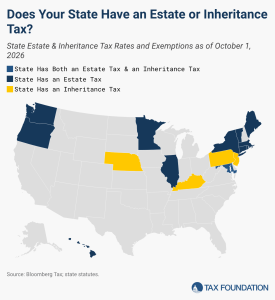
Oregon’s property tax system is moderately competitive, though the property tax burden relative to personal income is higher than in California and Washington. Additionally, the state imposes an estate tax with a maximum rate of 16 percent and the lowest estate tax exemption among states that levy the tax ($1 million), which further reduces the state’s competitiveness for high-net-worth individuals.
Imposing sales taxes on rental car companies’ fleet purchases, in addition to the sales and rental car excise taxes levied when those cars are rented, yields double taxation and causes harmful tax pyramiding.
In addition to the federal estate tax, which has a top marginal rate of 40 percent, 12 states and the District of Columbia impose estate taxes, while five states levy inheritance taxes.
Corporations in the United States pay federal corporate income taxes levied at a 21 percent rate. Forty-four states and D.C. also levy taxes on corporate income, with top marginal rates ranging from 2.5 percent in North Carolina to 11.5 percent in New Jersey.