Real Property Taxes in Europe, 2026
High property taxes levied not only on land but also on buildings and structures can discourage investment in infrastructure, which businesses would have to pay additional tax on.
3 min read
Nebraska has taken strides to improve its income tax competitiveness in recent years by reducing its individual and corporate income tax rates. Currently, the state’s graduated individual income tax rates range from 2.46 percent to 5.84 percent, and its corporate income tax rate is now a flat 5.2 percent. Despite these improvements, Nebraska maintains an uncompetitive “convenience of the employer rule,” which can lead to double taxation (with no offsetting credit) for remote employees working for businesses located in Nebraska—ultimately a disincentive for businesses to locate in the state if they want to be able to hire across the country. Nebraska also requires individual income tax filing and withholding for nonresidents working even a single day in the state.
Notably, Nebraska’s property taxes are on the high side regionally and nationally, and Nebraska is one of the few states that continues to impose an antiquated capital stock tax, which is assessed against the net worth of Nebraska corporations and imposed regardless of whether a firm makes a profit. The Nebraska Occupation Tax, as it is known in the state, is collected every other year, which complicates the filing process, since firms must track their net worths across two tax years. Nebraska also retains an inheritance tax, albeit on a declining share of beneficiaries, and is the only state to have adopted but then abandoned a tangible personal property tax de minimis exemption.
| Category | Rank | Rank Change | Score |
|---|---|---|---|
| Overall | 22 | 0 | 5.27 |
| Corporate Taxes | 14 | 6 | 5.52 |
| Individual Income Taxes | 26 | -1 | 5.35 |
| Sales Taxes | 12 | 0 | 5.41 |
| Property Taxes | 46 | -6 | 3.91 |
| Unemployment Insurance Taxes | 3 | 0 | 6.06 |


Get facts about taxes in your state and around the US
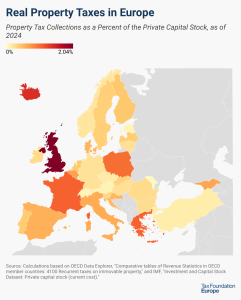
High property taxes levied not only on land but also on buildings and structures can discourage investment in infrastructure, which businesses would have to pay additional tax on.
3 min read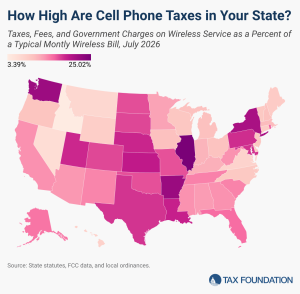
Applying the sales tax, a traditional broad-based consumption tax, is perfectly appropriate, but excessive targeted taxation of wireless services lacks the traditional justifications—a user-pays system or the internalization of social costs—for excise taxation, raising consumer costs and discouraging investment.
5 min read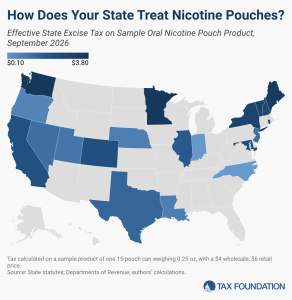
Oral nicotine pouches have rapidly become a popular option for consumers who want nicotine without the harmful combustion and chemicals of traditional cigarettes. As these alternative nicotine products (ANPs) successfully draw smokers to non-combustible nicotine consumption, many states have scrambled to incorporate these new products into their tax regimes.
6 min read