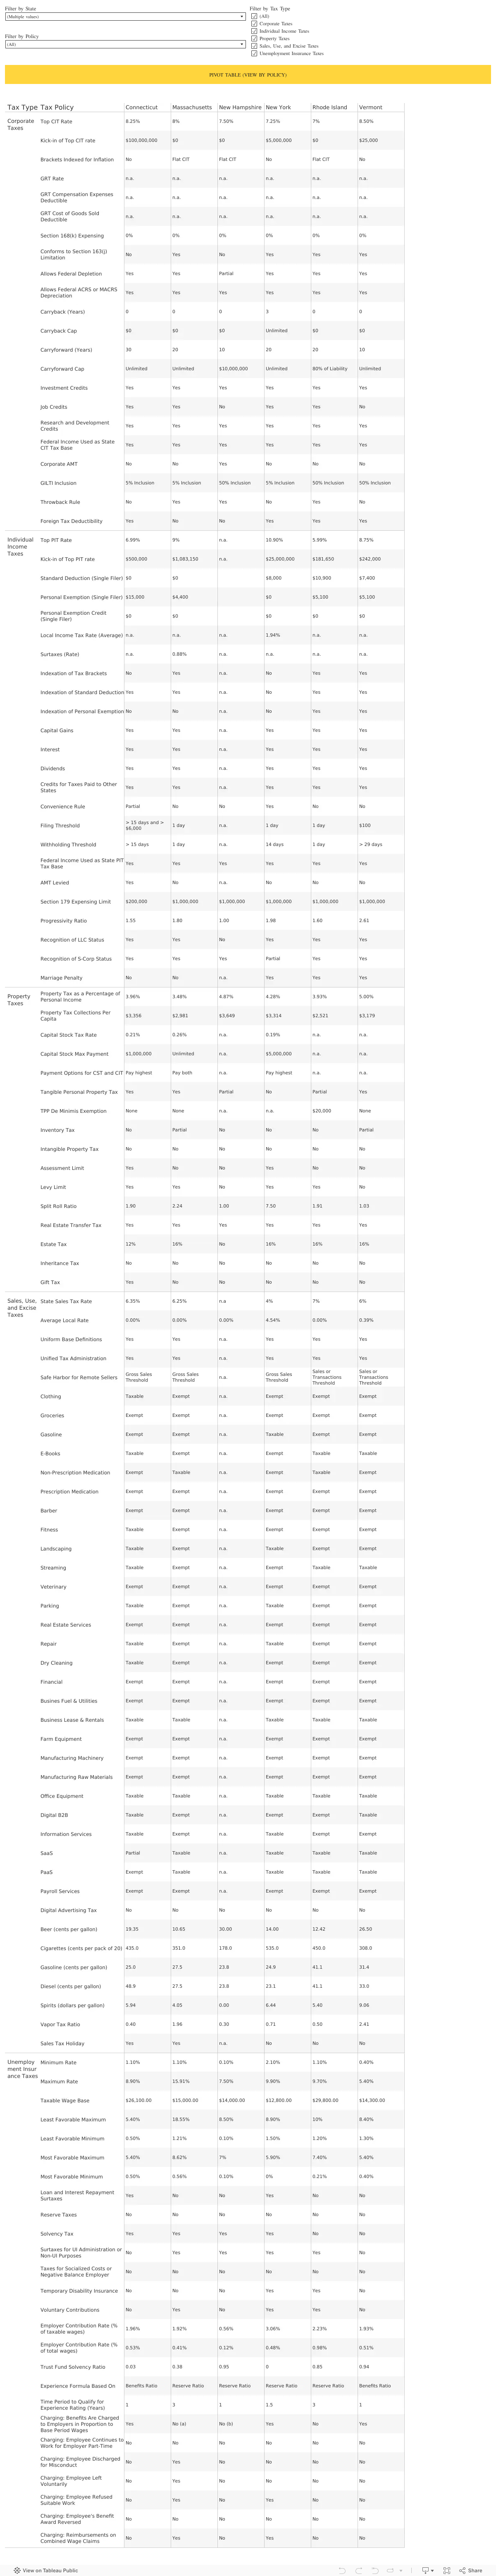
Massachusetts ranks among the bottom 10 states on the Index due to its overly burdensome individual income taxes, property taxes, and UI taxes. In 2022, Massachusetts voters amended the state constitution to impose an additional 4 percent surtax on income greater than $1 million, dismantling the state’s formerly competitive flat income tax and making Massachusetts less attractive for productive households and businesses. The Commonwealth is also an outlier in imposing a separate payroll tax for non-UI purposes.
Additionally, Massachusetts’ so-called corporate excise tax, which has a capital stock base component, imposes high burdens on businesses with large amounts of capital in Massachusetts and includes a throwback rule that exposes Massachusetts’ businesses to high tax burdens when they sell tangible property into states with which they do not have nexus. Furthermore, the state does not offer first-year expensing, discouraging in-state investment. Massachusetts also has an overly burdensome UI tax, with high rates, a solvency tax and surtax, and a lengthy experience rating qualifying period.
In addition to its hefty income tax burdens, especially for businesses, Massachusetts’ property taxes are among the highest in the nation, and the base includes some business inventory, though a levy limit, conventionally called Proposition 2 ½, does help reduce the further growth of property taxes. The state taxes commercial property more heavily than residential property, adding to businesses’ tax burdens. Additionally, Massachusetts levies both an estate tax and a real estate transfer tax.
Imposing sales taxes on rental car companies’ fleet purchases, in addition to the sales and rental car excise taxes levied when those cars are rented, yields double taxation and causes harmful tax pyramiding.
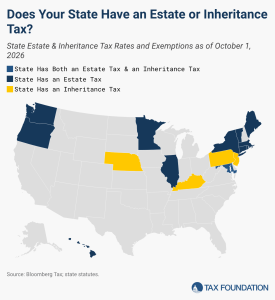
In addition to the federal estate tax, which has a top marginal rate of 40 percent, 12 states and the District of Columbia impose estate taxes, while five states levy inheritance taxes.
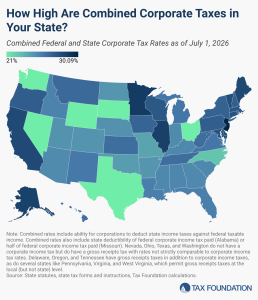
Corporations in the United States pay federal corporate income taxes levied at a 21 percent rate. Forty-four states and DC also levy taxes on corporate income, with top marginal rates ranging from 2.5 percent in North Carolina to 11.5 percent in New Jersey.