Idaho’s individual and corporate income taxes are imposed at a single rate, which was reduced from 5.695 percent to 5.3 percent in 2025. However, the state’s throwback rule is inefficient and taxes “nowhere income” in the state from which sales are made because the seller lacks sufficient nexus to be taxed in the destination state, leading to taxation in the wrong state at the wrong rate—making the corporate income tax more of a disincentive to in-state activity. Idaho also fails to conform to federal provisions to provide first-year expensing of business machinery and equipment purchases. Idaho is also among the minority of states that tax net CFC-tested income (NCTI), which replaced global intangible low-taxed income (GILTI), with a 15 percent inclusion.
Idaho has a generous de minimis exemption for tangible personal property, eliminating compliance costs for many smaller and mid-sized businesses. The state’s income tax has a 30-day withholding threshold but a single-day filing threshold, meaning that an individual who works even one day in the state is expected to file and remit taxes, even though the income would not be withheld by their employer.
Imposing sales taxes on rental car companies’ fleet purchases, in addition to the sales and rental car excise taxes levied when those cars are rented, yields double taxation and causes harmful tax pyramiding.
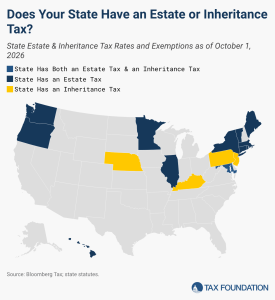
In addition to the federal estate tax, which has a top marginal rate of 40 percent, 12 states and the District of Columbia impose estate taxes, while five states levy inheritance taxes.
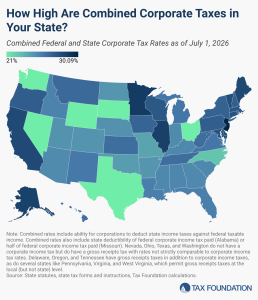
Corporations in the United States pay federal corporate income taxes levied at a 21 percent rate. Forty-four states and D.C. also levy taxes on corporate income, with top marginal rates ranging from 2.5 percent in North Carolina to 11.5 percent in New Jersey.