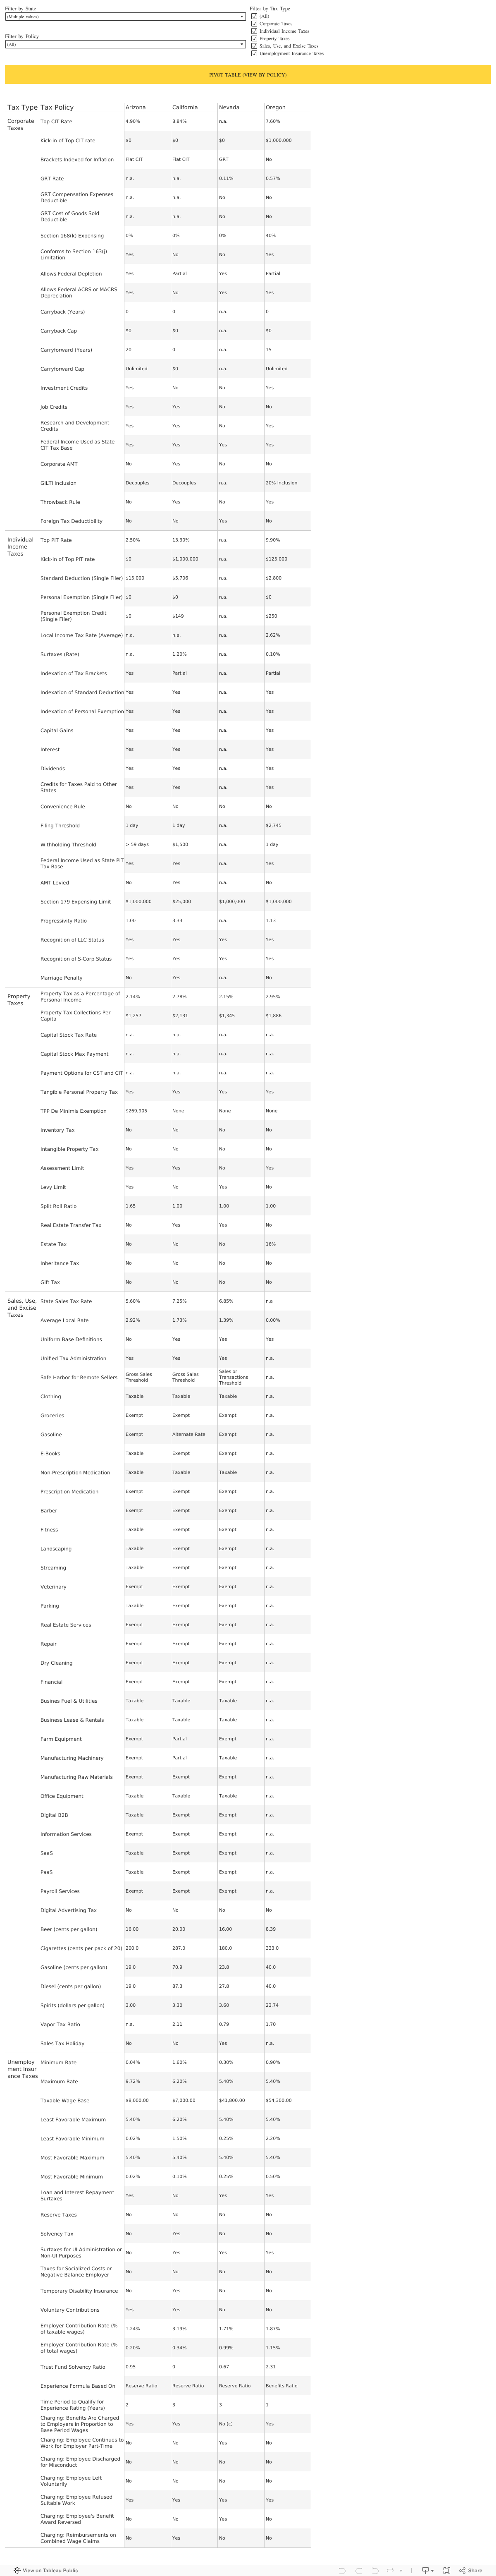
California combines high tax rates with an uncompetitive tax structure, yielding one of the worst rankings on the Index. The state has a great deal going for it, with its mild climate, excellent research universities, and the ongoing agglomeration effects of Silicon Valley (which is seeing a resurgence with the rise of generative AI), but a tax code that is uncompetitive and threatens to get worse is increasingly driving jobs to other states.
The state’s top marginal individual income tax rate of 13.3 percent is compounded by a 1.1 percent uncapped payroll tax, bringing the all-in top rate to 14.4 percent. Additionally, nonresidents must file income taxes if they work even a single day in the state, and California is one of only four states to still impose an alternative minimum tax.
California is the only state to deny all net operating loss carryforwards; the state’s NOL provisions have been suspended on multiple occasions and are not currently in effect. It is also the only state to use the outmoded ACRS depreciation system rather than MACRS, and does not allow any accelerated first-year expensing. California has a throwback rule, exposing in-state businesses to additional corporate tax liability for certain out-of-state income that would not be taxed elsewhere. The state is also dramatically out of conformity with the federal tax code as of the snapshot date of this Index, though legislation to bring conformity forward by a decade was on the governor’s desk at the time of publication. Even this conformity bill would be outdated from the start, however, predating changes adopted as part of 2025’s One Big Beautiful Bill Act (OBBBA). Delayed conformity adds to tax complexity, though California’s current 2015 conformity date has certain benefits: the state does not, for instance, currently incorporate global intangible low-taxed income (or net CFC-tested income under the OBBBA), which does not belong in state tax codes but has been incorporated by some states.
Property taxes in California are constrained by Proposition 13 and subsequent enactments that cap growth in taxable assessed value. This keeps property taxes lower than they would be otherwise—especially for long-time incumbent owners—but at the cost of significant distortions to property markets.
Imposing sales taxes on rental car companies’ fleet purchases, in addition to the sales and rental car excise taxes levied when those cars are rented, yields double taxation and causes harmful tax pyramiding.
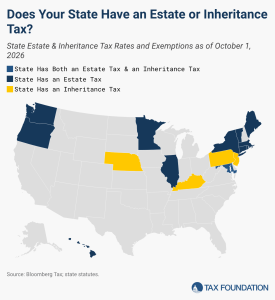
In addition to the federal estate tax, which has a top marginal rate of 40 percent, 12 states and the District of Columbia impose estate taxes, while five states levy inheritance taxes.
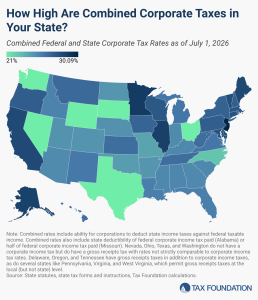
Corporations in the United States pay federal corporate income taxes levied at a 21 percent rate. Forty-four states and DC also levy taxes on corporate income, with top marginal rates ranging from 2.5 percent in North Carolina to 11.5 percent in New Jersey.