Washington forgoes an individual income tax on wage income due to constitutional constraints, though the state recently imposed a tax on high earners’ capital gains income, a policy that raised constitutional questions but ultimately secured the assent of the state supreme court. It became a graduated rate tax in 2025, with a top rate of 9.9 percent for gains above $1 million. The constitution has been similarly interpreted as blocking a corporate income tax, but Washington instead imposes a high multiple-rate gross receipts tax, called the Business & Occupation Tax. Because it is based on gross revenues rather than net income (profits), it yields very high rates of taxation on low-margin businesses and leads to tax pyramiding, where goods and services have the tax embedded several times over, imposed on each transaction within the production process.
The state’s sales tax, imposed atop the gross receipts tax, is not just a high rate but is also imposed on a base that includes an unusual share of business inputs, particularly in the digital products space. In 2025, lawmakers adopted legislation further expanding digital products taxation and notably including digital advertising in the base, which raises legal concerns along with economic ones. Washington also levies a progressive real estate transfer tax and the nation’s highest-rate estate tax, with the top rate raised to 35 percent in 2025, rivaling the 40 percent top federal rate. High UI taxes and an uncompetitive UI tax structure also contribute to the state’s poor Index ranking despite the state forgoing an individual income tax, which might otherwise be expected to yield a much more competitive tax environment.
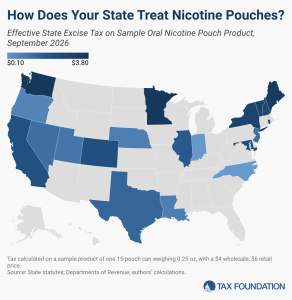
Oral nicotine pouches have rapidly become a popular option for consumers who want nicotine without the harmful combustion and chemicals of traditional cigarettes. As these alternative nicotine products (ANPs) successfully draw smokers to non-combustible nicotine consumption, many states have scrambled to incorporate these new products into their tax regimes.
Privacy concerns are a primary driver of opposition to vehicle miles traveled (VMT) tax systems, but VMT taxes do not need to invade drivers’ privacy to efficiently fund the roads.