Utah’s tax code features all major tax types, but the state ranks reasonably well on the Index because the taxes are imposed at competitive rates on relatively broad bases that introduce fewer economic distortions than rival states’ tax systems. Flat state-level individual and corporate income tax rates of 4.5 percent (with no local income taxes), imposed on reasonably broad bases, combine with extremely low real property taxes and a regionally competitive sales tax to produce a favorable overall tax climate, which is reflected in the state’s favorable Index rank. Lawmakers have consistently trimmed state income tax rates as the state continues to experience strong revenue collections.
Utah largely avoids excessive taxation of in-state capital investment. It forgoes capital stock and gross receipts taxes, does not impose a throwback rule, and conforms to federal provisions for the first-year expensing of capital investment. And while, unlike some of its rivals, Utah does tax tangible personal property (chiefly business machinery and equipment), it offers a de minimis exemption to eliminate compliance costs for smaller businesses. Lawmakers have also made great strides in reducing sales taxation of business inputs, which leads to tax pyramiding and discourages in-state production. The state does, however, include net CFC-tested income (NCTI), formerly global intangible low-taxed income (GILTI), in its corporate tax base, making it an outlier nationwide and particularly among lower-tax states.
Imposing sales taxes on rental car companies’ fleet purchases, in addition to the sales and rental car excise taxes levied when those cars are rented, yields double taxation and causes harmful tax pyramiding.
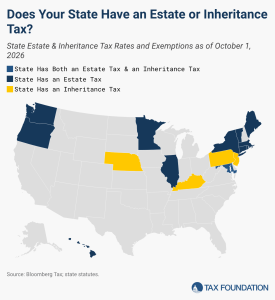
In addition to the federal estate tax, which has a top marginal rate of 40 percent, 12 states and the District of Columbia impose estate taxes, while five states levy inheritance taxes.
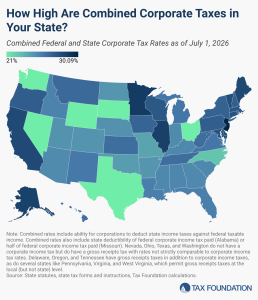
Corporations in the United States pay federal corporate income taxes levied at a 21 percent rate. Forty-four states and D.C. also levy taxes on corporate income, with top marginal rates ranging from 2.5 percent in North Carolina to 11.5 percent in New Jersey.