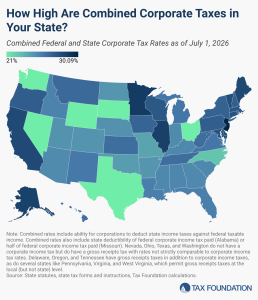
South Dakota is one of only two states to forgo individual income, corporate income, and gross receipts taxes. Consequently, the state relies heavily on its sales tax, which nevertheless retains a highly competitive rate, though one imposed on an overbroad base. It applies to most final personal consumption—which is appropriate—but also to a wide range of business inputs, which causes harmful tax pyramiding.
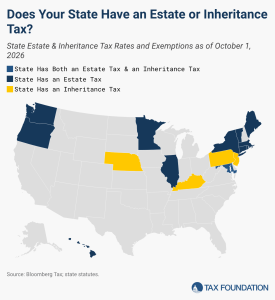
South Dakota relies on relatively high property taxes to fund local government, but the property tax base is competitive in that the property tax does not apply to tangible personal property or business inventory. Furthermore, the property tax applies to all classes of property uniformly, which is important for maintaining neutrality and preventing distortions, and the state does not have an estate or inheritance tax.
Imposing sales taxes on rental car companies’ fleet purchases, in addition to the sales and rental car excise taxes levied when those cars are rented, yields double taxation and causes harmful tax pyramiding.
In addition to the federal estate tax, which has a top marginal rate of 40 percent, 12 states and the District of Columbia impose estate taxes, while five states levy inheritance taxes.
Corporations in the United States pay federal corporate income taxes levied at a 21 percent rate. Forty-four states and DC also levy taxes on corporate income, with top marginal rates ranging from 2.5 percent in North Carolina to 11.5 percent in New Jersey.