Pennsylvania has a low, flat state-level individual income tax rate of 3.07 percent, but local earned income taxes (on a narrower base than the state income tax) dramatically increase overall levels of income taxation in the Commonwealth. Additionally, Pennsylvania maintains an uncompetitive “convenience of the employer rule,” which can lead to double taxation for remote employees working for businesses located in the Commonwealth—ultimately a disincentive for businesses to locate in the state if they want to be able to hire across the country. Pennsylvania also requires individual income tax filing and withholding for nonresidents working even a single day in the state.
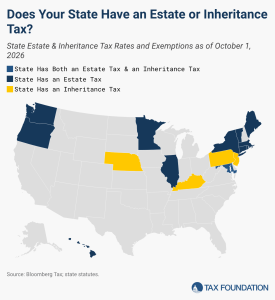
Pennsylvania’s corporate income tax rate is unusually high but is slowly phasing down to a competitive 4.99 percent. Pennsylvania is among the very few states to significantly cap net operating loss carryforwards, limiting them to 40 percent of taxable income, but recently enacted legislation will phase this cap up to 80 percent, in 10 percentage point increments, from 2025 through 2029. The Commonwealth does not conform to the Section 168(k) permanent full expensing offered at the federal level, and it also limits Section 179 first-year expensing for pass-through businesses to $25,000 in annual expenses. Pennsylvania also allows localities with existing gross receipts taxes to retain them, though new local gross receipts taxes cannot be created. It is one of five states that still impose an inheritance tax.
Local governments, meanwhile, operate under a patchwork of different state-imposed tax rules, with Philadelphia possessing unique authority given to no other jurisdiction. Consequently, Pennsylvania’s local taxes are among the more complex and burdensome in the country.
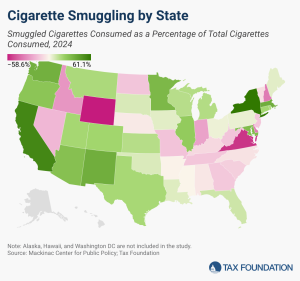
Cigarette smuggling is costly for states. We estimate that the forgone revenue from smuggled cigarettes totaled more than $4.6 billion in 2024. California lost nearly $1.4 billion in cigarette excise tax collections, and New York missed out on more than $1.2 billion.
Imposing sales taxes on rental car companies’ fleet purchases, in addition to the sales and rental car excise taxes levied when those cars are rented, yields double taxation and causes harmful tax pyramiding.
In addition to the federal estate tax, which has a top marginal rate of 40 percent, 12 states and the District of Columbia impose estate taxes, while five states levy inheritance taxes.