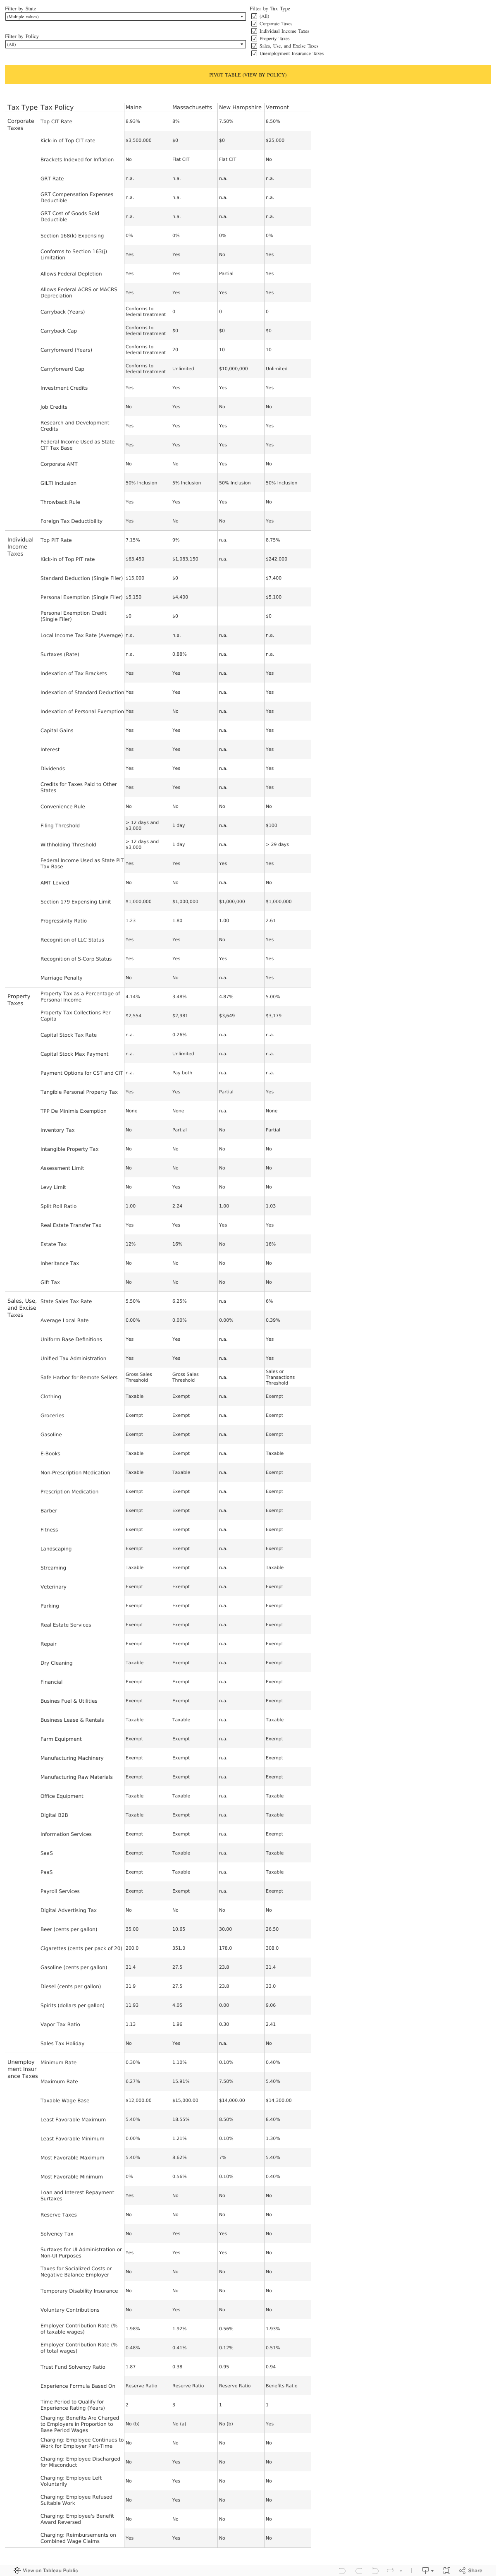
Like other states that forgo one or more major taxes, New Hampshire’s lack of an individual income tax or sales tax yields an extremely competitive overall ranking despite relatively lower rankings on the corporate income tax and property tax components. New Hampshire joined the ranks of the individual income tax-free states when its interest and dividends (I&D) tax was phased out in January 2025, further solidifying the state’s competitive standing.
The Granite State has recently taken steps to improve its corporate income tax structure by decoupling from the federal limitation on the deductibility of business net interest expenses, but New Hampshire has a short net operating loss (NOL) carryforward period of only 10 years, with a $10 million cap. Furthermore, the state does not offer bonus depreciation under Section 168(k), and it limits Section 179 expensing to $500,000. Additionally, New Hampshire has two different business taxes, the business profits tax and the business enterprise tax. The state is also penalized for its lack of conformity to federal schedules for the deductibility of natural resource depletion.
Without an individual income tax or sales tax, New Hampshire relies heavily on property taxes and corporate income taxes, with high rates that affect its scores on those components as a trade-off for its competitiveness compared to states that levy all the major taxes. Moving forward, New Hampshire could improve its competitiveness by adopting permanent full expensing and improving its treatment of NOLs.
Imposing sales taxes on rental car companies’ fleet purchases, in addition to the sales and rental car excise taxes levied when those cars are rented, yields double taxation and causes harmful tax pyramiding.
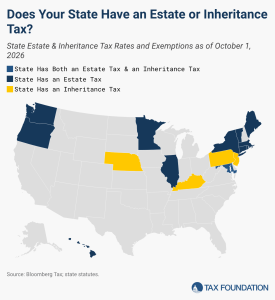
In addition to the federal estate tax, which has a top marginal rate of 40 percent, 12 states and the District of Columbia impose estate taxes, while five states levy inheritance taxes.
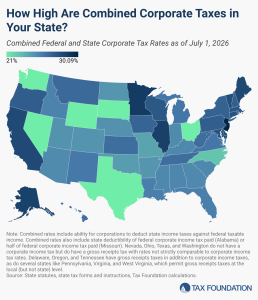
Corporations in the United States pay federal corporate income taxes levied at a 21 percent rate. Forty-four states and D.C. also levy taxes on corporate income, with top marginal rates ranging from 2.5 percent in North Carolina to 11.5 percent in New Jersey.