Nevada forgoes both individual and corporate income taxes, though it levies a low-rate payroll tax (for purposes other than unemployment insurance) that exclusively taxes wage income, and places a low multi-rate gross receipts tax, the Commerce Tax, on businesses. The Commerce Tax is structurally unsound, as it taxes gross revenue rather than profits, but it is imposed at rates low enough to make the tax’s distortions less damaging.
Nevada’s sales tax is higher than average, as an offset for not levying broad-based income taxes. Its remote seller threshold takes the number of transactions into account, whereas best practice is to adopt a dollar-denominated threshold. The state does not impose a capital stock tax, and, absent income taxes, avoids many of the structural questions faced by other states. However, the state’s unemployment insurance tax regime is relatively uncompetitive.
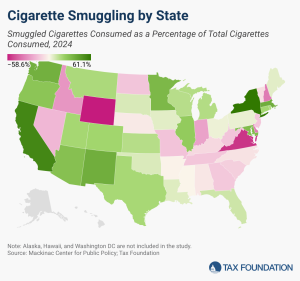
Cigarette smuggling is costly for states. We estimate that the forgone revenue from smuggled cigarettes totaled more than $4.6 billion in 2024. California lost nearly $1.4 billion in cigarette excise tax collections, and New York missed out on more than $1.2 billion.
Imposing sales taxes on rental car companies’ fleet purchases, in addition to the sales and rental car excise taxes levied when those cars are rented, yields double taxation and causes harmful tax pyramiding.
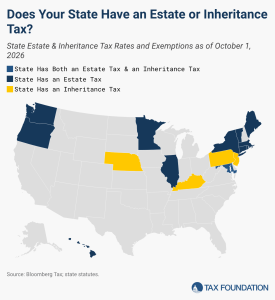
In addition to the federal estate tax, which has a top marginal rate of 40 percent, 12 states and the District of Columbia impose estate taxes, while five states levy inheritance taxes.