Kansas has a fairly standard tax code—with few features that make it either distinctly competitive or uncompetitive—and this is reflected in the state’s ranking near the middle of the pack. Kansas’ individual and corporate income taxes both have graduated-rate structures, with brackets, a standard deduction, and a personal exemption that are not indexed for inflation. Kansas’ top marginal individual and corporate income tax rates, as well as its combined state and average local sales tax rate, are all at or above the national median.
While Kansas exposes an outsized share of business income to its corporate income tax due to its throwback rule, the state does conform to the federal bonus depreciation allowance and federal net operating loss (NOL) provisions. The Sunflower State maintains a single point of sales tax administration for its state and local sales taxes, and its state and local sales tax bases largely match, with a couple of exceptions. Additionally, most of Kansas’ excise tax rates are relatively competitive compared to those in many other states.
Kansas’ property tax split roll ratio is fairly high, with commercial properties bearing a higher share of the property tax burden compared to residential properties, but by forgoing a capital stock tax and estate or inheritance tax, Kansas outperforms many of its peers on this component.
In 2025, lawmakers enacted legislation using tax triggers to provide individual and corporate income tax relief and, in time, to move to single-rate income taxes. These reforms will improve the state’s performance on the Index.
Imposing sales taxes on rental car companies’ fleet purchases, in addition to the sales and rental car excise taxes levied when those cars are rented, yields double taxation and causes harmful tax pyramiding.
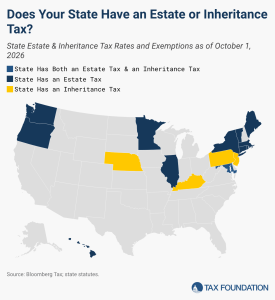
In addition to the federal estate tax, which has a top marginal rate of 40 percent, 12 states and the District of Columbia impose estate taxes, while five states levy inheritance taxes.
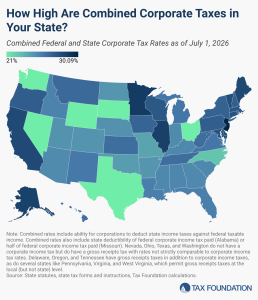
Corporations in the United States pay federal corporate income taxes levied at a 21 percent rate. Forty-four states and D.C. also levy taxes on corporate income, with top marginal rates ranging from 2.5 percent in North Carolina to 11.5 percent in New Jersey.