

Early property taxes, first implemented in feudal times, were levied primarily on land and paid mostly by farmers. In modern times, property taxes are also levied on assets like real estate and paid on a recurrent basis by individuals or legal entities.
2026 Data
2025
2024
2023
2020
2019

Expand or Collapse Table
Real Property Taxes in Europe, as of 2024
| Country | Property Tax as Share of Private Capital Stock | Real Property or Land Tax | Real Property or Land Taxes Deductible from Corporate Income Tax |
|---|---|---|---|
| Austria | 0.10% | Tax on Real Property | No |
| Belgium | 0.69% | Tax on Real Property (a) | Yes |
| Bulgaria | 0.26% | Tax on Real Property | Yes |
| Croatia | 0.54% | Tax on Real Property | Yes |
| Czech Republic | 0.16% | Tax on Real Property | Yes |
| Denmark | 0.55% | Tax on Real Property | Yes |
| Estonia | 0.09% | Land Tax | Yes |
| Finland | 0.42% | Tax on Real Property | Yes |
| France | 1.08% | Tax on Real Property | Yes |
| Georgia | 0.66% | Tax on Real Property | Yes |
| Germany | 0.22% | Tax on Real Property (b) | Yes |
| Greece | 1.08% | Tax on Real Property | Yes |
| Hungary | 0.24% | Tax on Real Property | Yes |
| Iceland | 1.43% | Tax on Real Property | No |
| Ireland | 0.28% | Tax on Real Property | Yes |
| Italy | 0.61% | Tax on Real Property | No |
| Latvia | 0.38% | Tax on Real Property | Yes |
| Liechtenstein | 0.00% | None | NA |
| Lithuania | 0.24% | Tax on Real Property | Yes |
| Luxembourg | 0.05% | Tax on Real Property | Yes |
| Malta | 0.00% | None | NA |
| Moldova | 0.05% | Tax on Real Property | Yes |
| Netherlands | 0.40% | Tax on Real Property | Yes |
| Norway | 0.20% | Tax on Real Property | Yes |
| Poland | 1.01% | Tax on Real Property | Yes |
| Portugal | 0.39% | Tax on Real Property | Yes |
| Romania | 0.27% | Tax on Real Property | Yes |
| Slovak Republic | 0.34% | Tax on Real Property | Yes |
| Slovenia | 0.31% | Tax on Real Property | No |
| Spain | 0.58% | Tax on Real Property | Yes |
| Sweden | 0.36% | Tax on Real Property | Yes |
| Switzerland | 0.08% | Tax on Real Property | Yes |
| Turkey | 0.14% | Tax on Real Property | Yes |
| United Kingdom | 2.04% | Tax on Real Property | Yes |
| Canada | 1.581% | Tax on Real Property | Yes |
| United States (for comparison) | 1.882% | Tax on Real Property | Yes |
(a) Tax on the imputed rent of properties. Applies to machinery.
(b) Deviations at the state level effective from 2025. Baden-Württemberg operates a land value tax.
Source: Calculations for "Property Tax as Share of Private Capital Stock" are based on 2024 data from OECD Data Explorer, "Comparative tables of Revenue Statistics in OECD member countries: 4100 Recurrent taxes on immovable property," http://data-explorer.oecd.org/s/1se; and IMF, "Investment and Capital Stock Dataset: Private capital stock (current cost)," https://www.imf.org/external/np/fad/publicinvestment/#5. For the type of property tax and whether it is deductible, see PwC, "Worldwide Tax Summaries," https://taxsummaries.pwc.com/ (2025 data).

Expand or Collapse Table
Real Property Taxes in Europe, as of 2023
| Country | Property Tax as Share of Private Capital Stock | Real Property or Land Tax | Real Property or Land Taxes Deductible from Corporate Income Tax |
|---|---|---|---|
| Austria | 0.110% | Tax on Real Property | No |
| Belgium | 0.761% | Tax on Real Property (a) | Yes |
| Czech Republic | 0.004% | Tax on Real Property | Yes |
| Denmark | 0.110% | Tax on Real Property | Yes |
| Estonia | 0.112% | Land Tax | No |
| Finland | 0.427% | Tax on Real Property | Yes |
| France | 1.134% | Tax on Real Property | Yes |
| Germany | 0.233% | Tax on Real Property (b) | Yes |
| Greece | 1.164% | Tax on Real Property | Yes |
| Hungary | 0.001% | Tax on Real Property | No |
| Iceland | 0.010% | Tax on Real Property | No |
| Ireland | 0.306% | Tax on Real Property | Yes |
| Italy | 0.659% | Tax on Real Property | No |
| Latvia | 0.445% | Tax on Real Property | Yes |
| Liechtenstein | 0.000% | None | NA |
| Lithuania | 0.293% | Tax on Real Property | Yes |
| Luxembourg | 0.054% | Tax on Real Property | Yes |
| Malta | 0.000% | None | NA |
| Netherlands | 0.518% | Tax on Real Property | Yes |
| Norway | 0.021% | Tax on Real Property | Yes |
| Poland | 0.245% | Tax on Real Property | Yes |
| Portugal | 0.444% | Tax on Real Property | Yes |
| Slovak Republic | 0.314% | Tax on Real Property | Yes |
| Slovenia | 0.333% | Tax on Real Property | No |
| Spain | 0.645% | Tax on Real Property | No |
| Sweden | 0.035% | Tax on Real Property | Yes |
| Switzerland | 0.095% | Tax on Real Property | Yes |
| Turkey | 0.008% | Tax on Real Property | Yes |
| United Kingdom | 2.570% | Tax on Real Property | Yes |
| United States (for comparison) | 1.812% | Tax on Real Property | Yes |
(a) Tax on the imputed rent of properties. Applies to machinery.
(b) Deviations at the state level effective from 2025.
Source: Calculations for "Property Tax as Share of Private Capital Stock" are based on 2023 data from OECD Data Explorer, "Comparative tables of Revenue Statistics in OECD member countries: 4100 Recurrent taxes on immovable property," http://data-explorer.oecd.org/s/1se; and IMF, "Investment and Capital Stock Dataset: Private capital stock (current cost)," https://www.imf.org/external/np/fad/publicinvestment/#5. For the type of property tax and whether it is deductible, see PwC, "Worldwide Tax Summaries," https://taxsummaries.pwc.com/ (2025 data).
Expand or Collapse Table
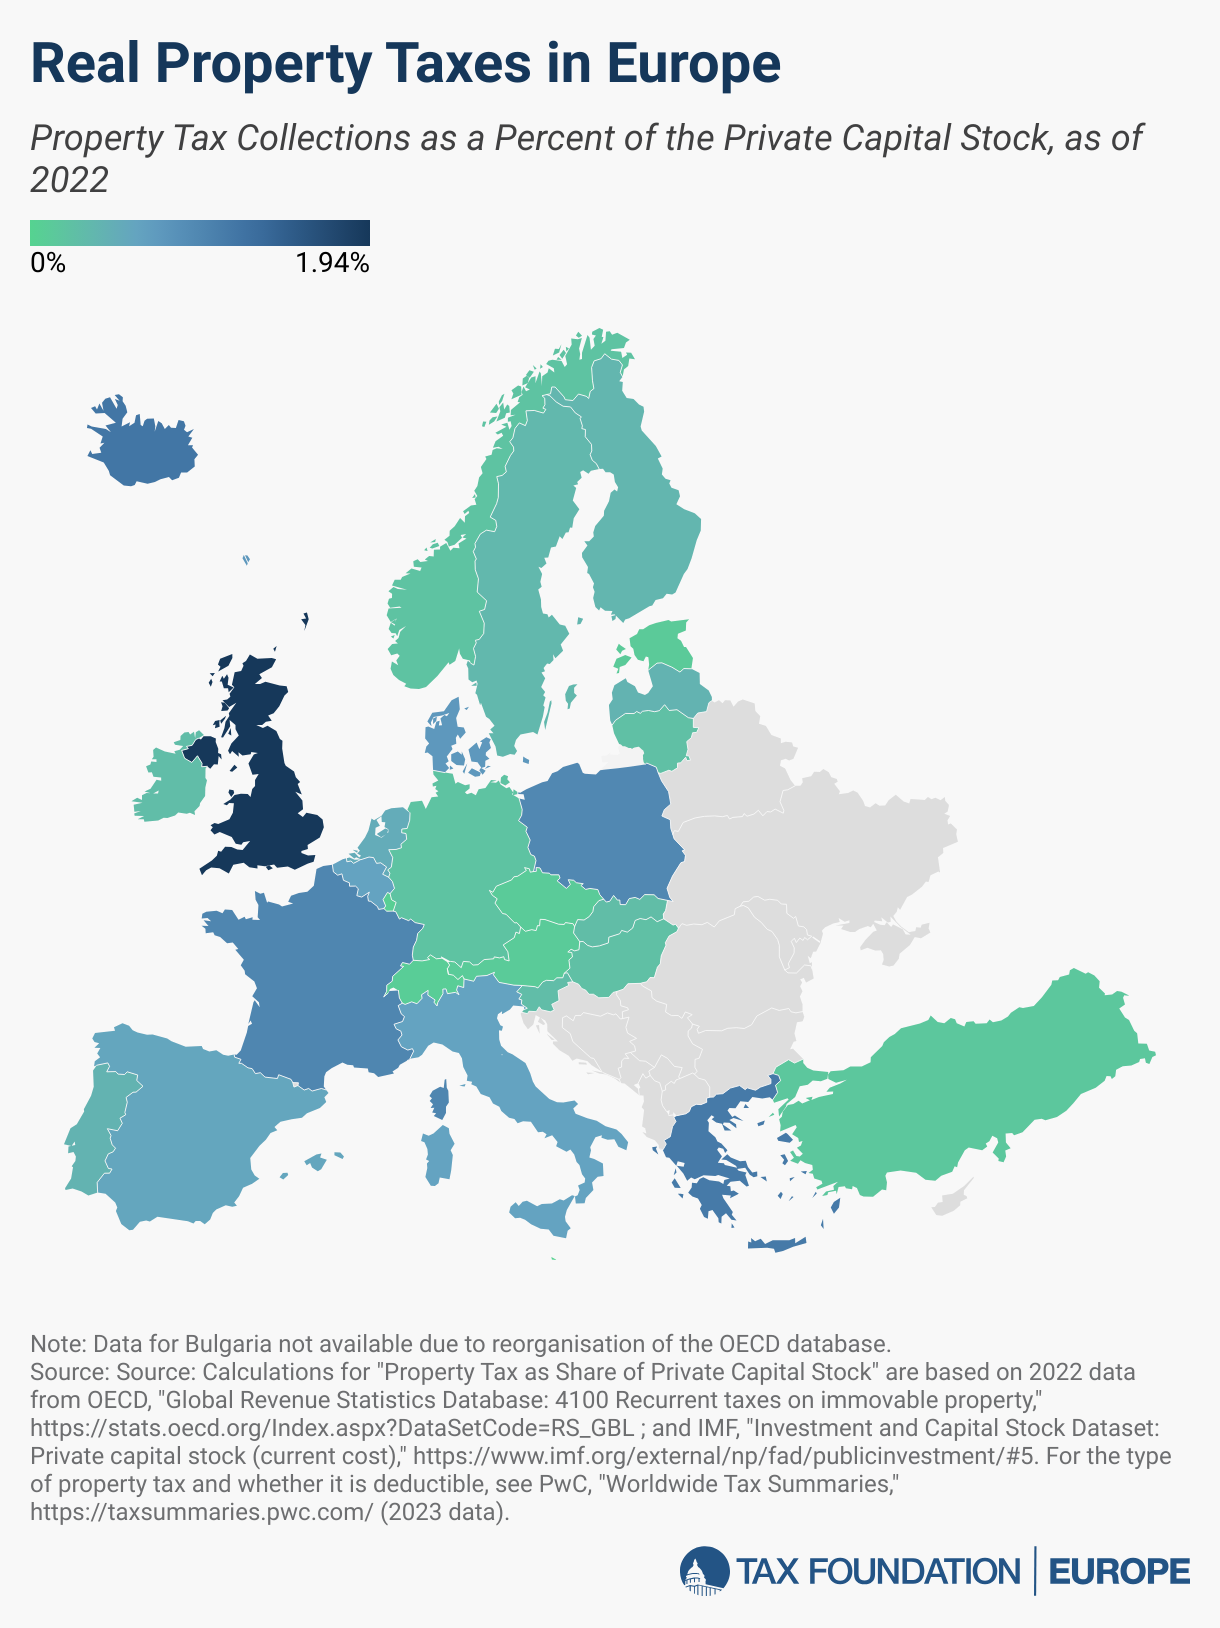
Real Property Taxes in Europe, as of 2022
| Country | Property Tax as Share of Private Capital Stock | Real Property or Land Tax | Real Property or Land Taxes Deductible from Corporate Income Tax |
|---|---|---|---|
| Austria | 0.10% | Tax on Real Property | No |
| Belgium | 0.62% | Tax on Real Property (a) | Yes |
| Czech Republic | 0.10% | Tax on Real Property | Yes |
| Denmark | 0.75% | Tax on Real Property | Yes |
| Estonia | 0.11% | Land Tax | No |
| Finland | 0.38% | Tax on Real Property | Yes |
| France | 0.98% | Tax on Real Property | Yes |
| Germany | 0.21% | Tax on Real Property | Yes |
| Greece | 1.13% | Tax on Real Property | No |
| Hungary | 0.25% | Tax on Real Property | No |
| Iceland | 1.18% | Tax on Real Property | No |
| Ireland | 0.29% | Tax on Real Property | Yes |
| Italy | 0.62% | Tax on Real Property | No |
| Latvia | 0.41% | Tax on Real Property | Yes |
| Liechtenstein | 0.00% | None | NA |
| Lithuania | 0.25% | Tax on Real Property | Yes |
| Luxembourg | 0.05% | Tax on Real Property | Yes |
| Malta | 0.00% | None | NA |
| Netherlands | 0.51% | Tax on Real Property | Yes |
| Norway | 0.21% | Tax on Real Property | Yes |
| Poland | 0.95% | Tax on Real Property | Yes |
| Portugal | 0.41% | Tax on Real Property | Yes |
| Slovak Republic | 0.28% | Tax on Real Property | Yes |
| Slovenia | 0.29% | Tax on Real Property | No |
| Spain | 0.58% | Tax on Real Property | No |
| Sweden | 0.35% | Tax on Real Property | Yes |
| Switzerland | 0.08% | Tax on Real Property | Yes |
| Turkey | 0.15% | Tax on Real Property | Yes |
| United Kingdom | 1.94% | Tax on Real Property | Yes |
| United States (for comparison) | 1.80% | Tax on Real Property | Yes |
(a) Tax on the imputed rent of properties. Applies to machinery.
(b) Data for Bulgaria not available due to reorganisation of the OECD database.
Source: Calculations for "Property Tax as Share of Private Capital Stock" are based on 2022 data from OECD, "Global Revenue Statistics Database: 4100 Recurrent taxes on immovable property," https://stats.oecd.org/Index.aspx?DataSetCode=RS_GBL; and IMF, "Investment and Capital Stock Dataset: Private capital stock (current cost)," https://www.imf.org/external/np/fad/publicinvestment/#5. For the type of property tax and whether it is deductible, see PwC, "Worldwide Tax Summaries," https://taxsummaries.pwc.com/ (2023 data).
Data compiled by Alex Mengden
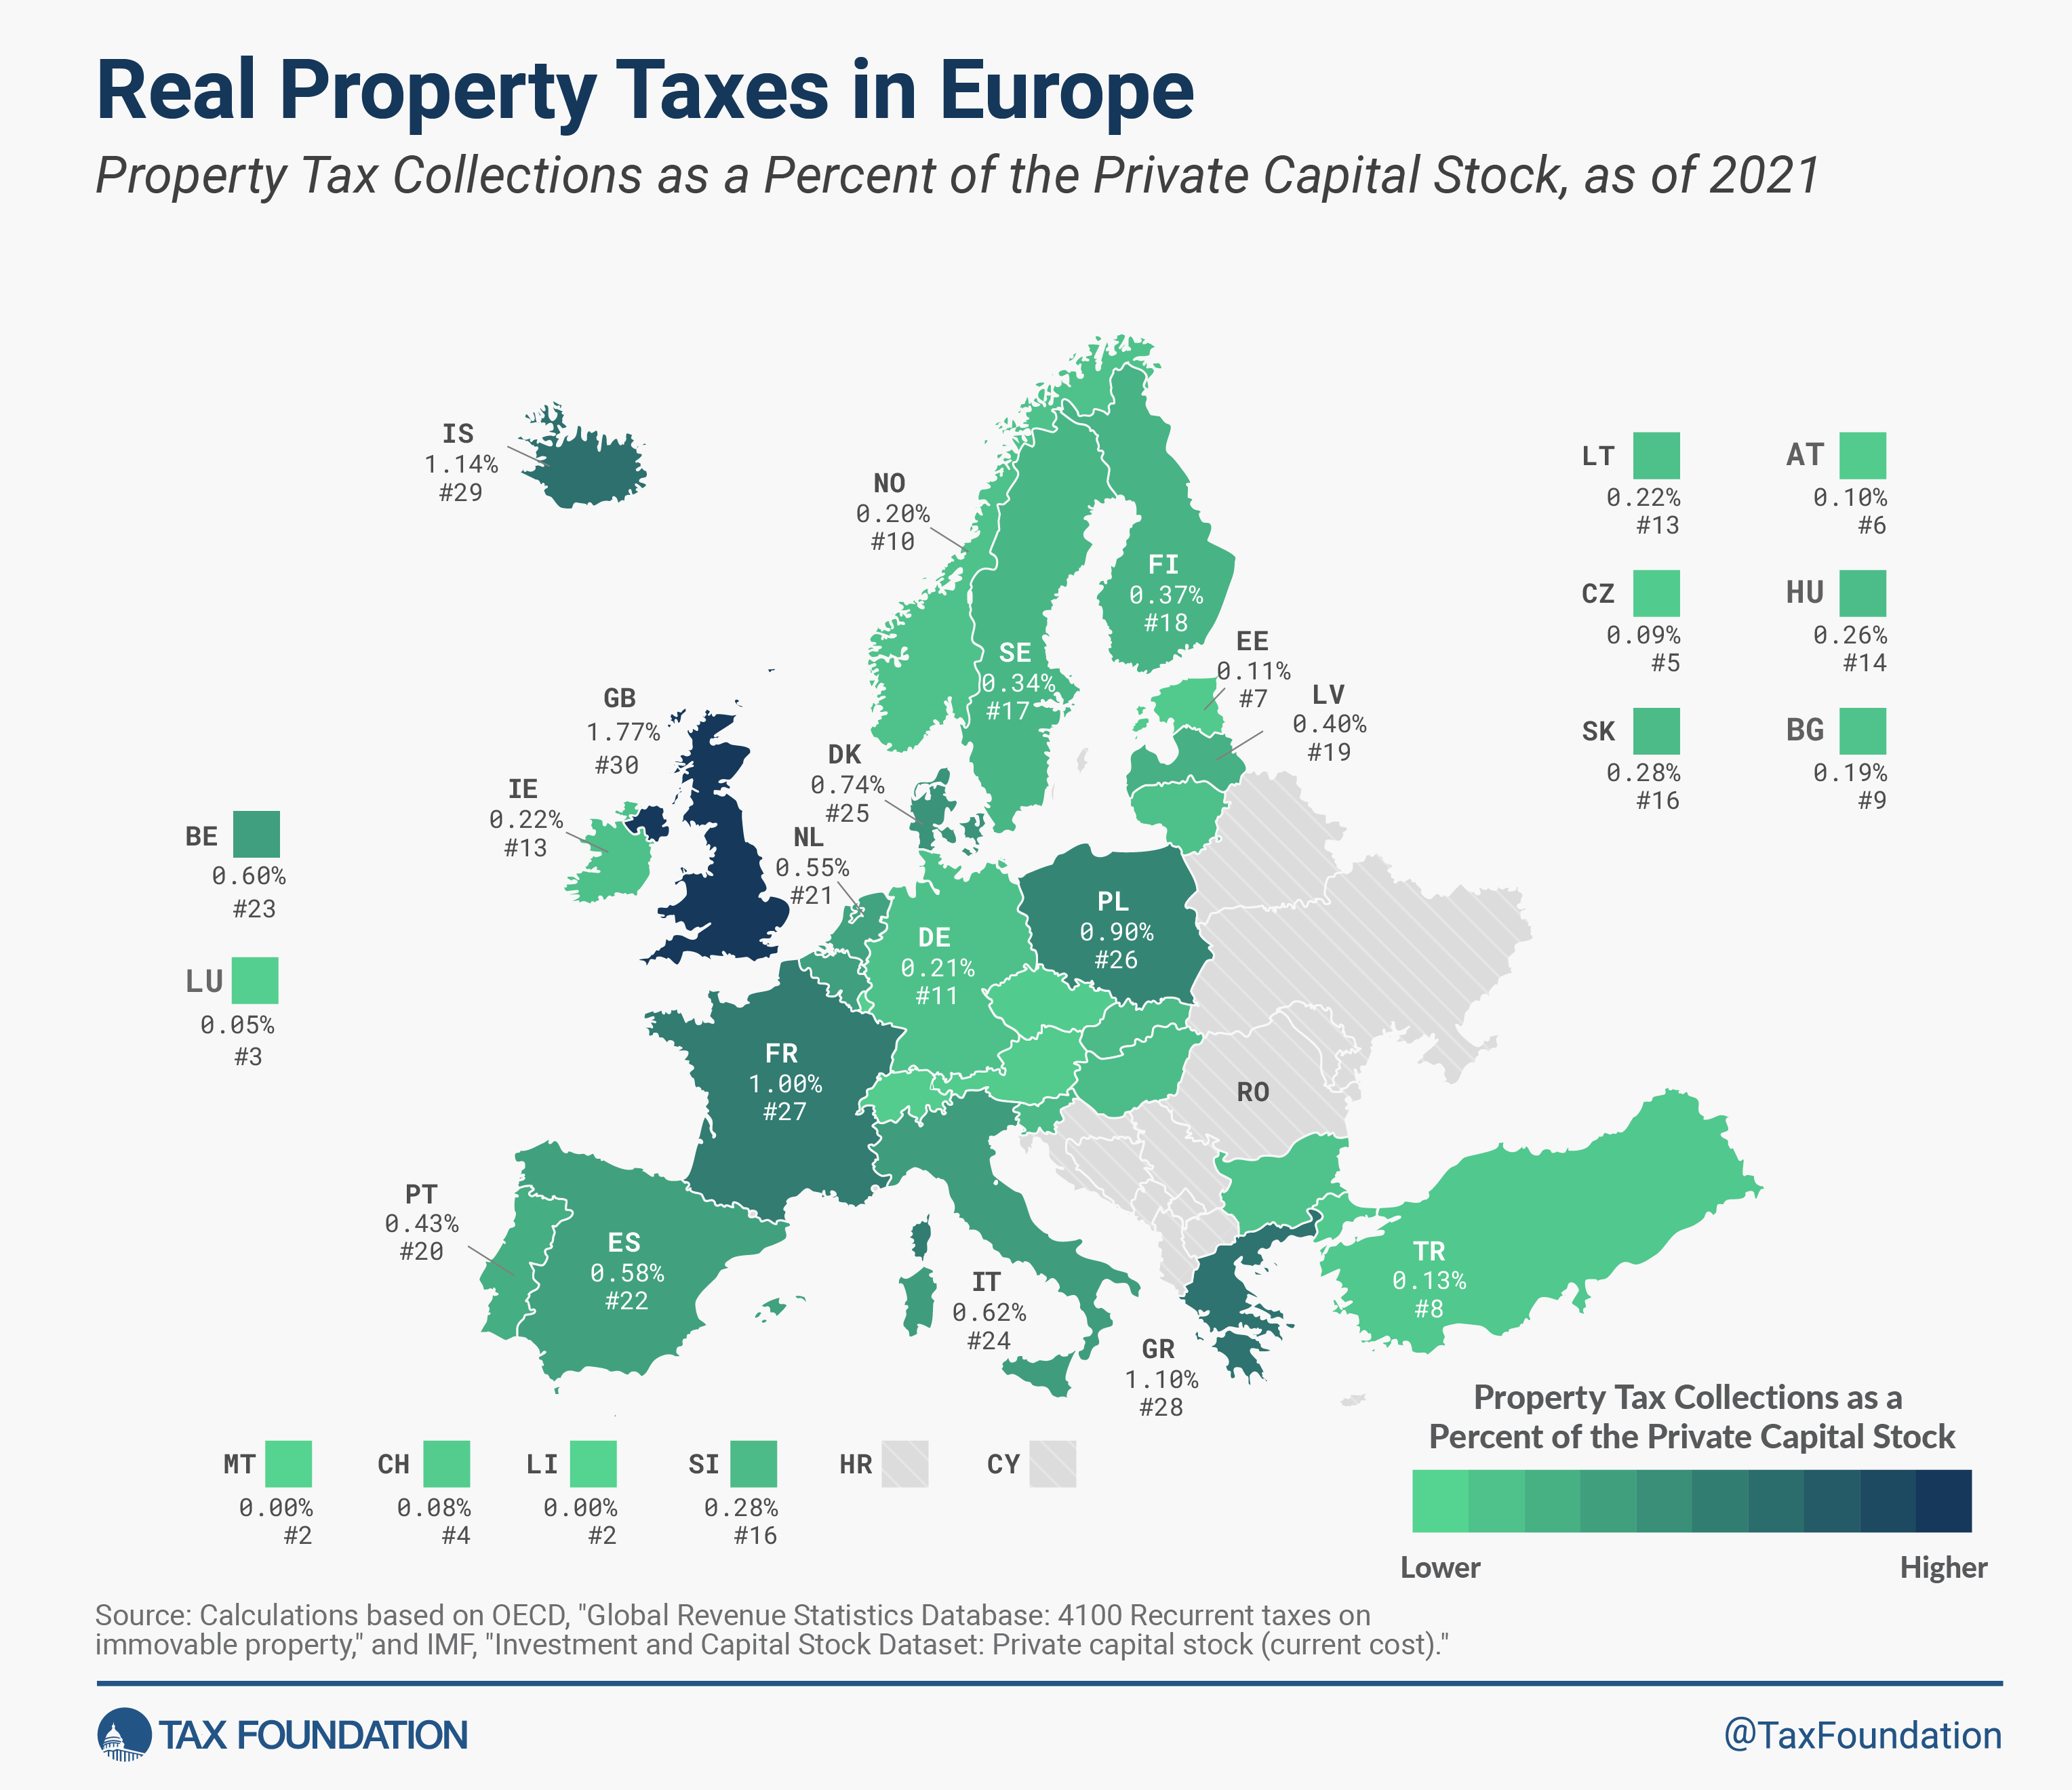
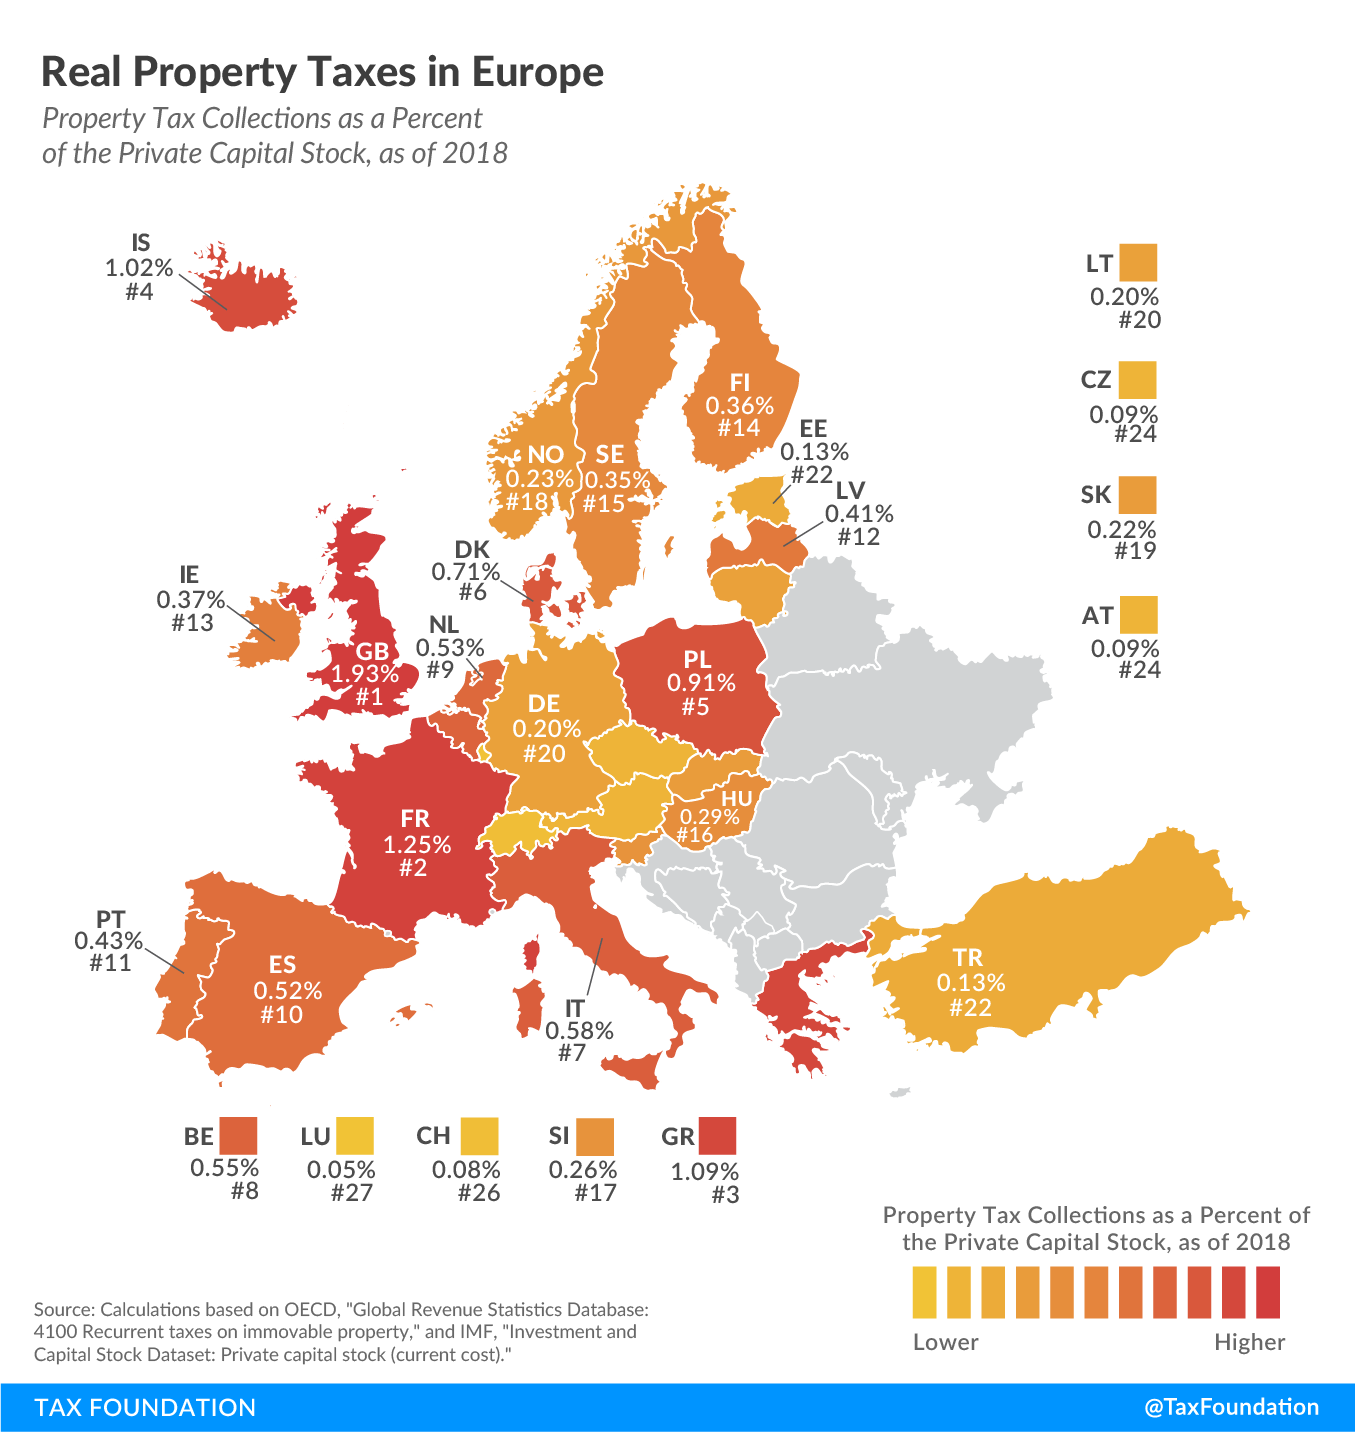
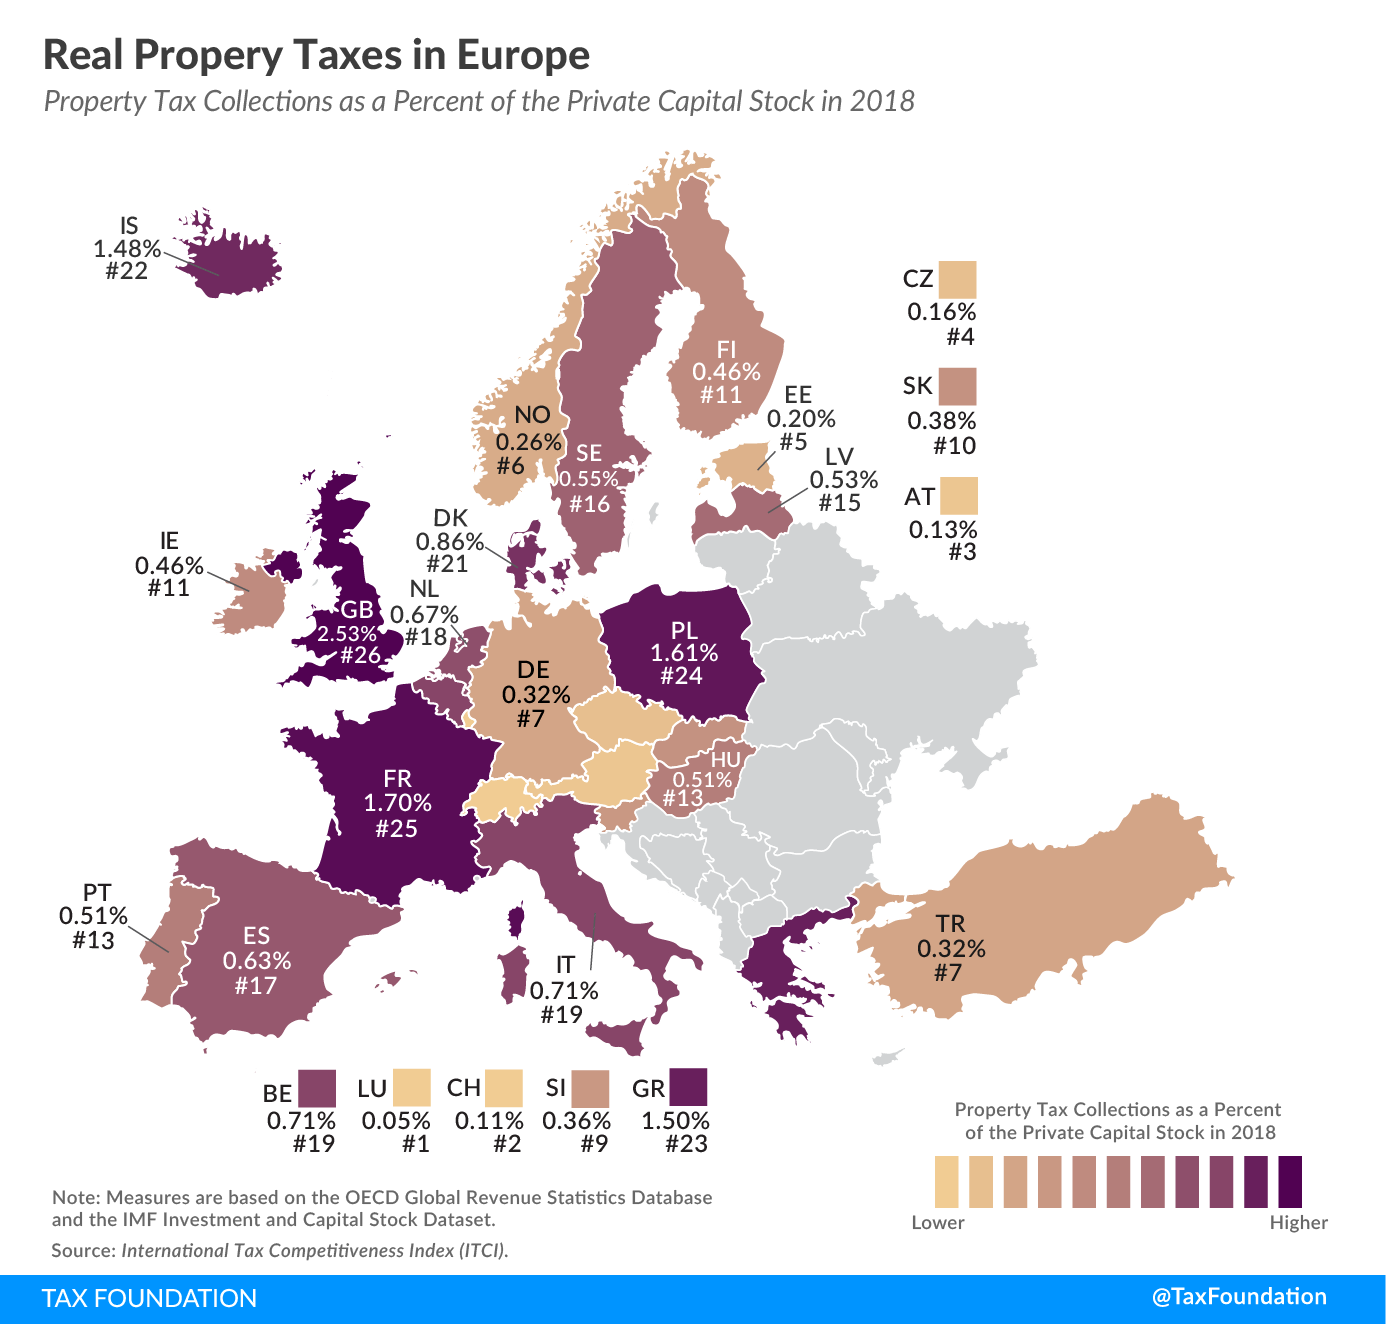
Ideally, property taxes can give local governments a valuable fiscal incentive to permit new development and offer a way to fund local public services whose value is capitalized into property prices. However, high property taxes levied not only on land but also on buildings and structures can also discourage investment in those assets, which businesses would have to pay additional taxA tax is a mandatory payment or charge collected by local, state, and national governments from individuals or businesses to cover the costs of general government services, goods, and activities. on. For this reason, businesses may choose to locate away from places with high property taxes.
Two of the 34 European countries covered here, Liechtenstein and Malta, do not levy any recurrent taxes on property at all. Estonia is the sole country on this map to tax only land, meaning that its real property taxA property tax is primarily levied on immovable property like land and buildings, as well as on tangible personal property that is movable, like vehicles and equipment. Property taxes are the single largest source of state and local revenue in the U.S. and help fund schools, roads, police, and other services. is the most efficient.
Of the 32 countries that levy property taxes, 28 allow businesses to deduct property or land taxes from corporate income, which mitigates the tax burden and encourages businesses to invest. Four countries—Austria, Iceland, Italy, and Slovenia—prohibit the deduction of property taxes from business income, leading to double taxationDouble taxation is when taxes are paid twice on the same dollar of income, regardless of whether that’s corporate or individual income. of business properties.
Luxembourg and Moldova raise the lowest property tax revenues as a share of their private capital stock, at around 0.05 percent. Switzerland and Estonia follow at 0.08 and 0.09 percent, respectively. The highest property taxes as a share of the private capital stock occur in the United Kingdom (2.04 percent), Iceland (1.43 percent), and France (1.08 percent).
On average, the revenue raised from recurrent property taxes in the 32 European countries covered that have a property tax lies at 0.45 percent of their private capital stocks. In contrast, the United States raises as much as 1.88 percent of its private capital stock in property taxes.
For the 16 European countries that record how property tax revenues are split between businesses and households, households remit around 60 percent of total property tax revenue, ranging from only 7.4 percent of receipts in the Slovak Republic to 71.4 percent in France.
Recent Changes
Starting from 2025, Germany is devolving its property tax baseThe tax base is the total amount of income, property, assets, consumption, transactions, or other economic activity subject to taxation by a tax authority. A narrow tax base is non-neutral and inefficient. A broad tax base reduces tax administration costs and allows more revenue to be raised at lower rates. to the state level. The state of Baden-Württemberg used this opportunity to apply property taxes only to the value of land. Croatia introduced a recurrent property tax in 2025, levied on the square metres of land and floor area.
Stay informed on the tax policies impacting you.
Subscribe to our free newsletter to get the latest tax data, news and analysis.
SubscribeAbout the Author
Alex Mengden is an Economist at the Tax Foundation, where he focuses on international tax issues and tax policy in Europe. He holds a BA in philosophy and economics from the University of Bayreuth and an MSc in economics from the Ludwig Maximilian University of Munich.