Real Property Taxes in Europe, 2026
High property taxes levied not only on land but also on buildings and structures can discourage investment in infrastructure, which businesses would have to pay additional tax on.
3 min read
Alex Mengden is an Economist at the Tax Foundation, where he focuses on international tax issues and tax policy in Europe. He holds a BA in philosophy and economics from the University of Bayreuth and an MSc in economics from the Ludwig Maximilian University of Munich.
Prior to joining the Tax Foundation, Alex tutored undergraduate classes in public finance at LMU Munich and worked on economic policy research for institutions across Europe and the United States. He currently lives in Berlin, Germany.
High property taxes levied not only on land but also on buildings and structures can discourage investment in infrastructure, which businesses would have to pay additional tax on.
3 min read
On September 15th, Canada announced that full expensing for machinery, equipment, and patent rights will be made permanent and broadened from around 15 percent to two thirds of business capital investment.
6 min read
Poland has one of the most restrictive approaches to the tax treatment of losses in the OECD. Loss carryover provisions allow businesses to deduct their losses in one year against taxable income in another, smoothing their taxable income over time. Their absence or restriction leads to firms with more variable profits and losses over time being taxed at higher rates, penalizing risky investment, such as research and development (R&D), and business expansion.
16 min read
Poland taxes its individual business owners through alternative regimes and a series of thresholds, several of them sharp notches that imply significant tax costs for businesses crossing them.
11 min read
The EU Tax Omnibus proposal would create an EU-wide minimum standard for full expensing, but it confines that standard to qualifying tangible assets used in research and development (R&D) rather than to broader asset classes.
16 min read
Because withholding taxes can create double taxation and administrative friction even where foreign tax credits are available, the European Commission’s 2026 Tax Omnibus proposal to eliminate them on dividend, interest, and royalty payments between EU companies regardless of holding percentage would foster stronger cross-border savings and investment.
6 min read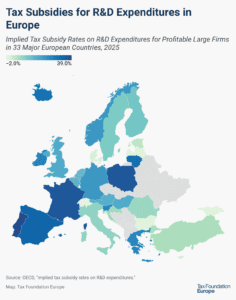
Many countries incentivize business investment in research and development (R&D), intending to foster innovation. A common approach is to provide direct government funding for R&D activity. However, a significant number of jurisdictions also offer R&D tax incentives.
5 min read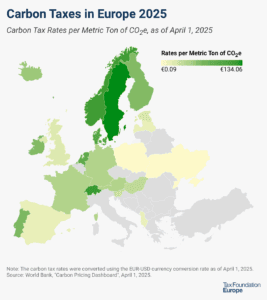
In recent years, several countries have taken measures to reduce carbon emissions, including instituting environmental regulations, emissions trading systems (ETSs), and carbon taxes.
5 min read
Worldwide, 175 countries—including all major European countries—levy a value-added tax (VAT) on goods and services. However, to reduce compliance and administrative costs, most countries have VAT exemption thresholds: if a business is below a certain annual revenue threshold, it is not required to participate in the VAT system.
3 min read
Fourteen countries in Europe—Belgium, Finland, France, Greece, Hungary, Ireland, Italy, Malta, Poland, the Slovak Republic, Spain, Switzerland, Turkey, and the United Kingdom—currently levy a type of financial transaction tax.
3 min read
Debates over tax fairness and anti-avoidance rules have dominated European tax policy circles for over a decade. However, as geoeconomic pressures increase around the world, policymakers are looking for ways to boost European competitiveness and economic growth.
18 min read
Carryover provisions help businesses “smooth” their risk and income, making the tax code more neutral across investments and over time.
5 min read
Shifting Germany’s tax mix away from labor to consumption remains a sound policy route to strengthen the country’s labor supply, but further eroding the VAT base with preferential rates for selected goods and services would counteract this goal by depleting the extra revenue for labor tax cuts while providing less-targeted relief for low-income households.
6 min read
To make the taxation of labor more efficient, policymakers should understand their country’s tax wedge and how their tax burden funds government services.
5 min read
Capital gains taxes create a bias against saving, leading to a lower level of national income by encouraging present consumption over investment.
4 min read
Structural reforms such as broadening tax bases, improving cost recovery, and shifting toward less distortive taxes can improve competitiveness without necessarily reducing revenue.
7 min read
The variety of approaches to taxation among European countries creates a need to evaluate these systems relative to each other. For that purpose, we have developed the European Tax Policy Scorecard—a relative comparison of European countries’ tax systems.
55 min read
Denmark (55.9 percent), France (55.4 percent), and Austria (55 percent) levy the highest top personal income tax rates in Europe.
4 min read
More than 175 countries worldwide—including all major European countries—levy a value-added tax (VAT) on goods and services. EU Member States’ VAT rates vary across countries, though they’re somewhat harmonized by the EU.
5 min read
Corporate tax reform can strengthen Chile’s economic growth at a minimal revenue cost by reinstating full expensing and adopting a territorial tax system to align its cross-border rules with the international standard.
5 min read