Real Property Taxes in Europe, 2026
High property taxes levied not only on land but also on buildings and structures can discourage investment in infrastructure, which businesses would have to pay additional tax on.
3 min read
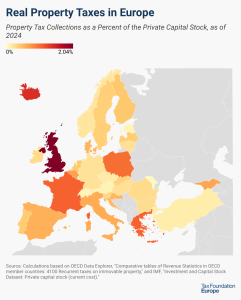
High property taxes levied not only on land but also on buildings and structures can discourage investment in infrastructure, which businesses would have to pay additional tax on.
3 min read
The European Union’s revised Tobacco Excise Directive (TED) is the latest proposal from Brussels that raises questions about the role that the EU plays in relation to the Member States.
7 min read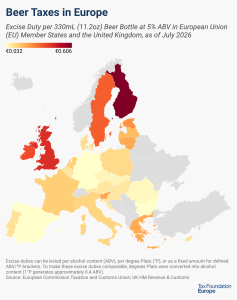
With much of the continent celebrating Oktoberfest, it is a great time to examine beer taxes across Europe. Hefty beer taxes increase the price consumers pay for their libations.
5 min read
While economic levers like sanctions and tariffs have long been recognized as geoeconomic tools, tax policies have rarely been considered a part of this toolkit.
36 min read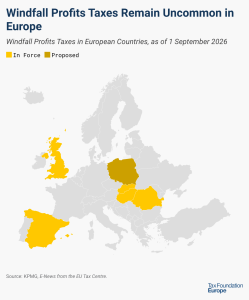
As energy prices have declined, European countries have switched the focus of their windfall profits taxes—a one-time tax levied on a company or industry when economic conditions result in large, unexpected profits—from energy providers to the banking and financial sector.
7 min read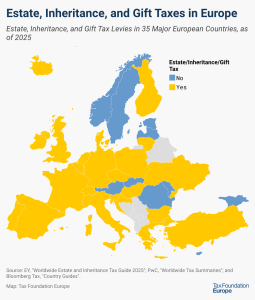
Twenty-four out of the 35 European countries covered in this map currently levy estate, inheritance, or gift taxes.
4 min read
Poland taxes its individual business owners through alternative regimes and a series of thresholds, several of them sharp notches that imply significant tax costs for businesses crossing them.
11 min read
Though they are often framed as affecting only the richest households, the economic effects of wealth taxes extend much further by reducing capital formation, discouraging entrepreneurship, curtailing wage and employment growth, and ultimately weakening the overall economy.
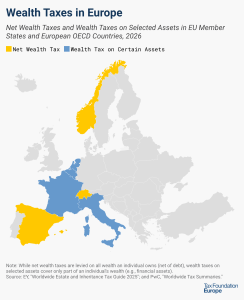
Wealth taxes not only collect little revenue and create legal uncertainty, but an OECD report argues that they can also disincentivize entrepreneurship, harming innovation and long-term growth.
5 min read
The EU Tax Omnibus proposal would create an EU-wide minimum standard for full expensing, but it confines that standard to qualifying tangible assets used in research and development (R&D) rather than to broader asset classes.
16 min read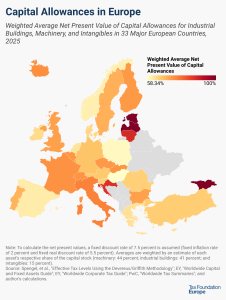
Although sometimes overlooked in discussions about corporate taxation, capital allowances play an important role in a country’s corporate tax base and can impact investment decisions—with far-reaching economic consequences.
6 min read
Retail prices make poor targets for excise tax policy, often reflecting factors that have little to do with the underlying reasons for which an excise tax is levied in the first place. Unfortunately, the World Health Organization (WHO) has a growing preference for using tax share of retail price (tax incidence) as a primary policy target.
6 min read
Because withholding taxes can create double taxation and administrative friction even where foreign tax credits are available, the European Commission’s 2026 Tax Omnibus proposal to eliminate them on dividend, interest, and royalty payments between EU companies regardless of holding percentage would foster stronger cross-border savings and investment.
6 min read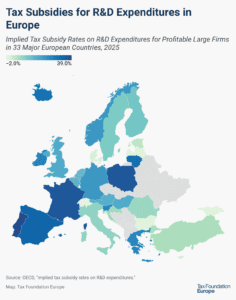
Many countries incentivize business investment in research and development (R&D), intending to foster innovation. A common approach is to provide direct government funding for R&D activity. However, a significant number of jurisdictions also offer R&D tax incentives.
5 min read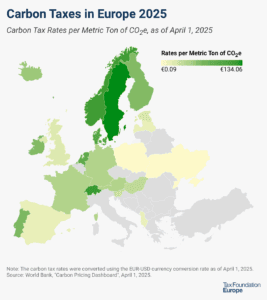
In recent years, several countries have taken measures to reduce carbon emissions, including instituting environmental regulations, emissions trading systems (ETSs), and carbon taxes.
5 min read
The new data disclosures will draw significant attention in 2026 and beyond. However, because the data is rooted in financial accounting concepts, affected by timing issues, and shaped by inconsistent reporting regimes, it is poorly suited for drawing strong conclusions about tax policy or corporate behavior.
7 min read
Digital services taxes address a real concern—the need to adapt taxation to the digital economy—but they are not the right solution. They raise limited revenue, are often passed on to consumers rather than large digital firms, create economic distortions, increase complexity and compliance costs, negatively impact innovation and competitiveness, and risk international retaliation.

Since digital services taxes generate little revenue, place the cost on European consumers and not on large digital companies as intended, and risk escalating trade disputes, policymakers should rethink their strategy.
14 min read
Europe’s turn toward the UN is ultimately not a sign that governments are ready to resolve fundamental disputes over taxing rights. If anything, international cooperation on the goal that matters most—fair treatment of cross-border trade—is crumbling.

The Reform UK proposal to exempt overtime pay from income tax—framed as a “hard work bonus”—may be politically appealing, but it’s a flawed idea that undermines economic fairness, distorts labor markets, and jeopardizes tax revenues.
4 min read