When taxpayers sell capital assets like real property or corporate stock, net earnings on those sales (capital gains) are generally subject to taxA tax is a mandatory payment or charge collected by local, state, and national governments from individuals or businesses to cover the costs of general government services, goods, and activities., and net losses (capital losses) can generally be deducted when calculating income tax liability.
One major shortcoming of current capital gains taxation is that the tax basis, or the purchase price of an asset, is not indexed for inflationInflation is when the general price of goods and services increases across the economy, reducing the purchasing power of a currency and the value of certain assets. The same paycheck covers less goods, services, and bills. It is sometimes referred to as a “hidden tax,” as it leaves taxpayers less well-off due to higher costs and “bracket creep,” while increasing the government’s spendin. As a result, capital gains are measured in nominal dollars, with the original purchase price subtracted from the sale price without any adjustment for the value of money over time. This means taxpayers are taxed on a combination of real gains and fictitious income that does not reflect an actual increase in purchasing power (although the tax code provides some accommodations, such as for qualifying sales of owner-occupied homes and properties transferred to heirs). In some cases, this lack of inflation indexingInflation indexing refers to automatic cost-of-living adjustments built into tax provisions to keep pace with inflation. Absent these adjustments, income taxes are subject to “bracket creep” and stealth increases on taxpayers, while excise taxes are vulnerable to erosion as taxes expressed in nominal dollars, rather than rates, slowly lose value. can be significant enough that taxpayers owe taxes on what appears to be a capital gain on paper, but is, in real terms, a net loss.
The federal tax code partially addresses this shortcoming through the preferential treatment of long-term capital gains. Long-term capital gains, defined as net gains on assets held for more than one year, are taxed under a separate rate schedule with lower rates and different brackets. Depending on a taxpayer’s overall taxable incomeTaxable income is the amount of income subject to tax, after deductions and exemptions. Taxable income differs from—and is less than—gross income. , long-term capital gains are taxed at rates of 0 percent, 15 percent, or 20 percent.
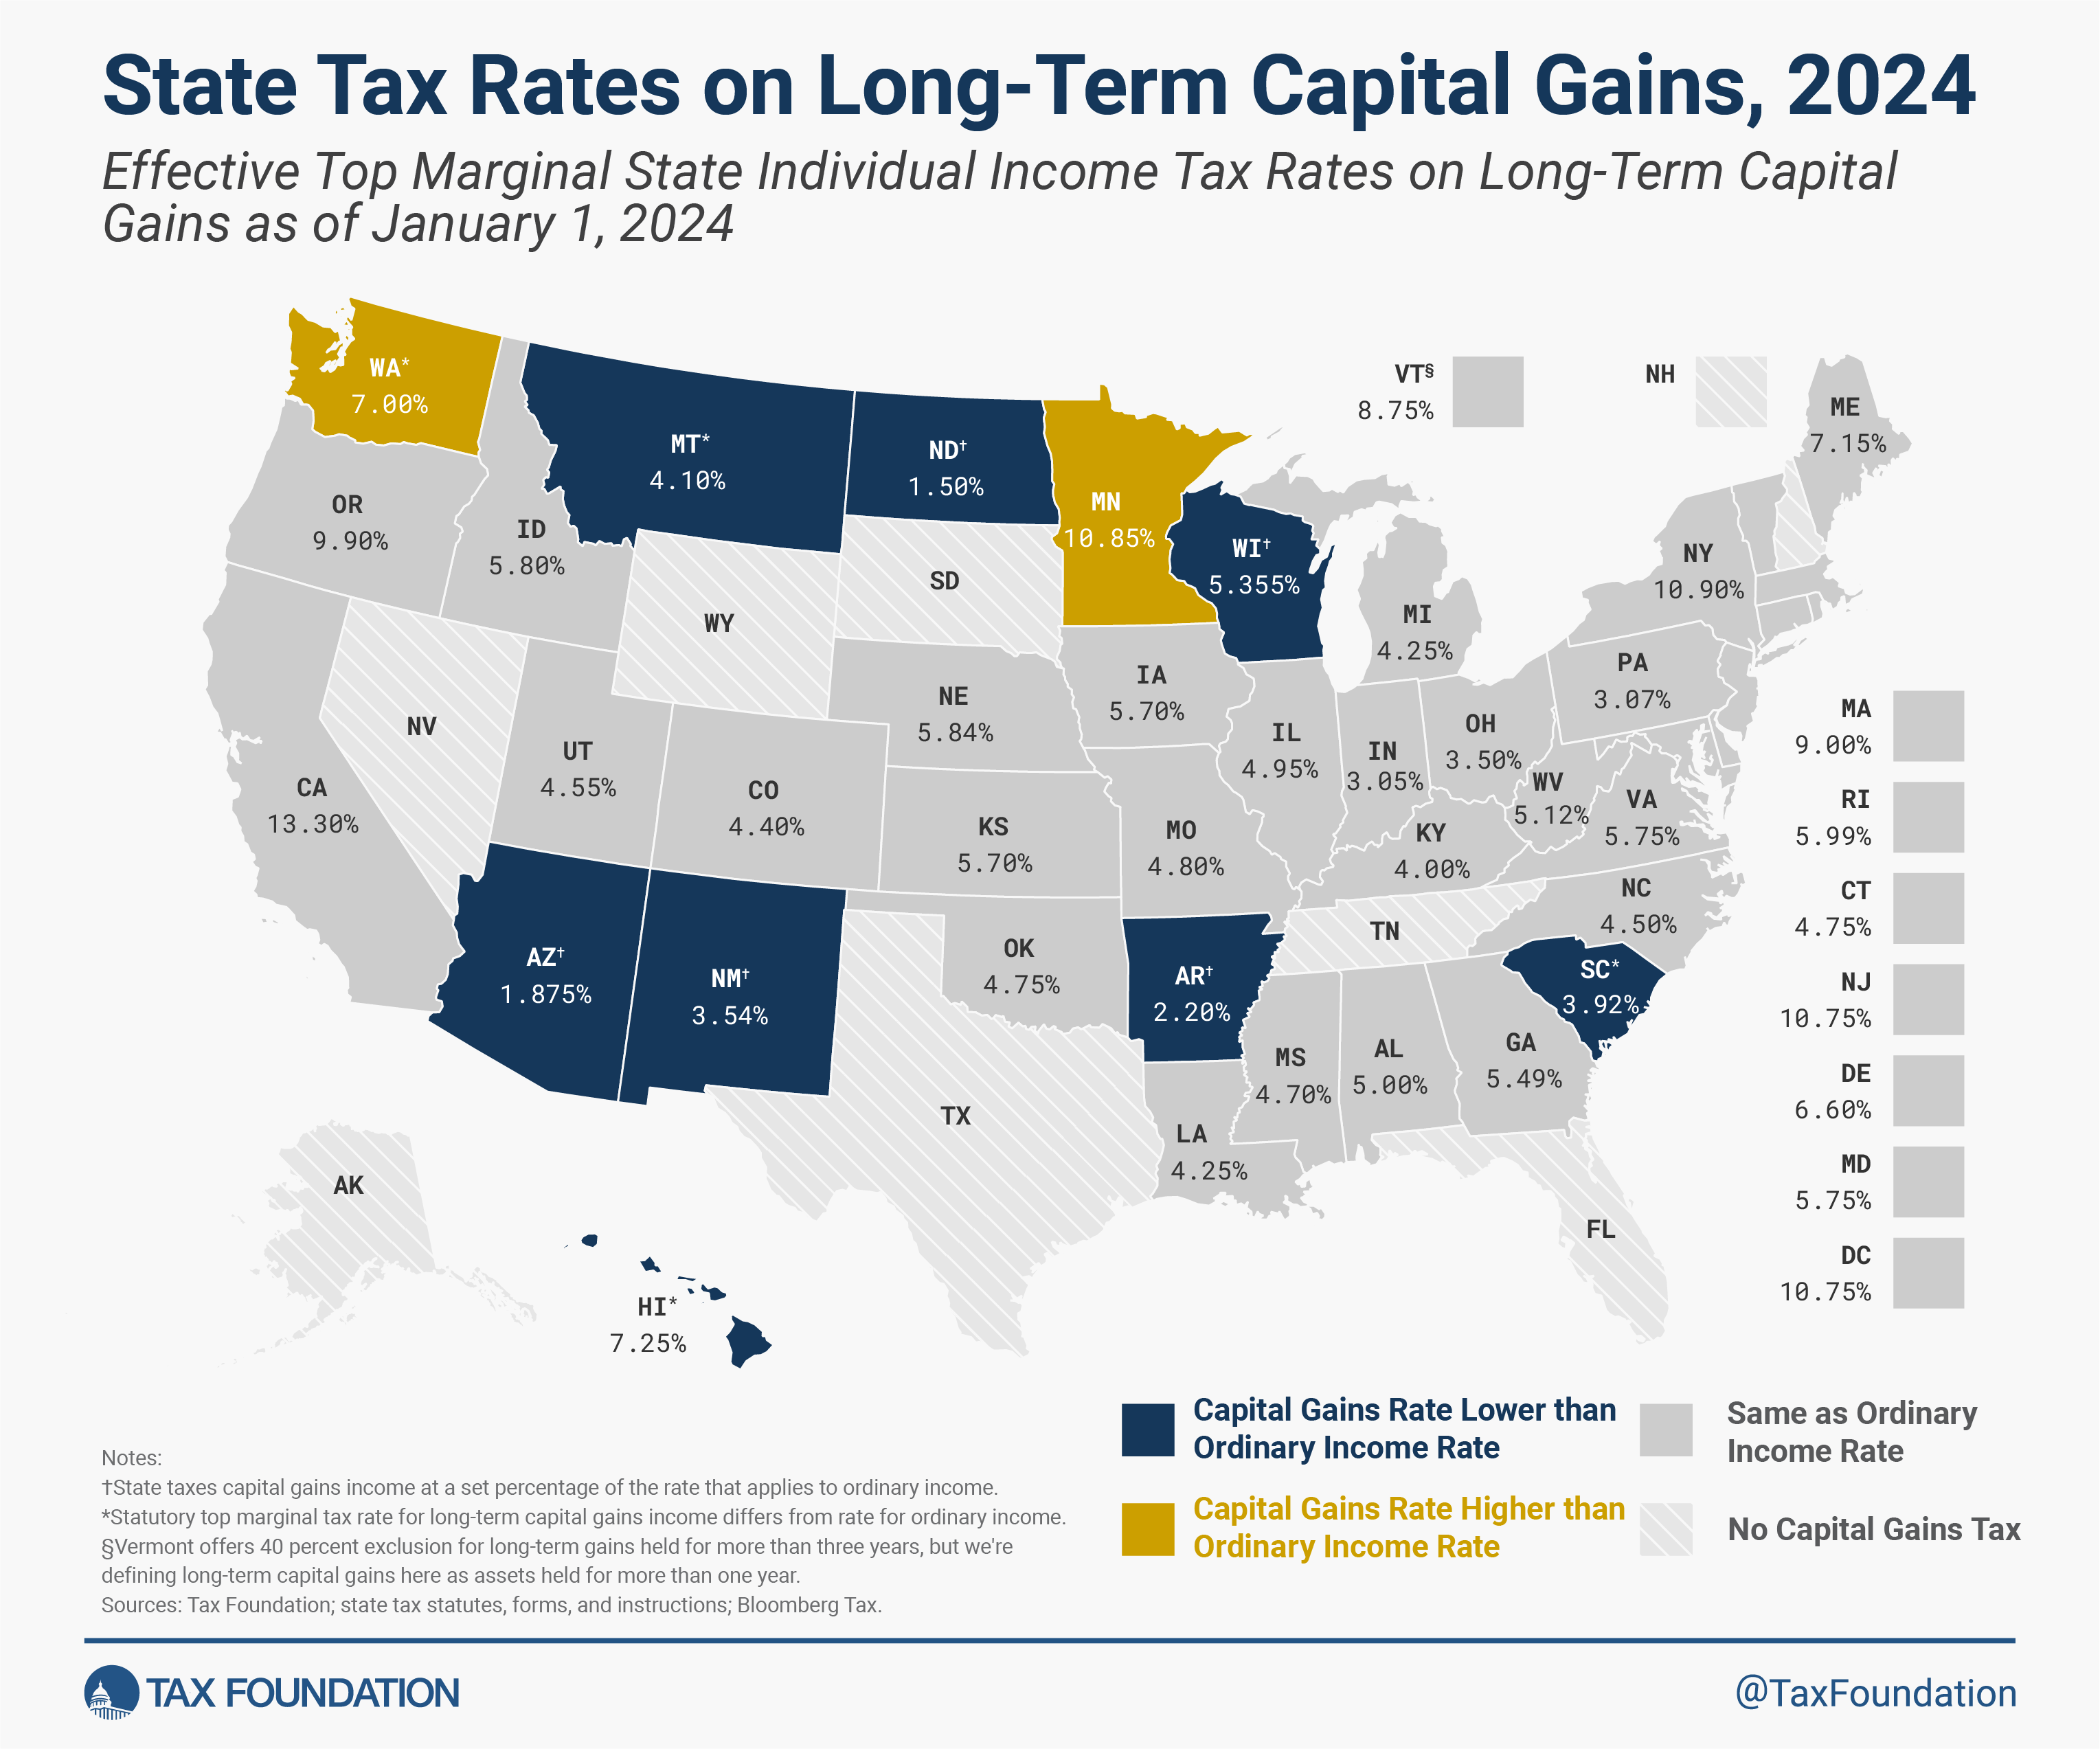
At the state level, accommodating the effects of inflation is less commonly seen. Thirty states and the District of Columbia overtax capital gains income simply by subjecting capital gains to the same rate schedule that applies to ordinary income.
Three states—Maryland, Minnesota, and Washington—expose some capital gains to higher rates than those that apply to ordinary income. Specifically, Maryland adds an additional 2 percent capital gains surtaxA surtax is an additional tax levied on top of an already existing business or individual tax and can have a flat or progressive rate structure. Surtaxes are typically enacted to fund a specific program or initiative, whereas revenue from broader-based taxes, like the individual income tax, typically cover a multitude of programs and services. to the state income tax due on income exceeding $350,000; Minnesota taxes most capital gains at ordinary rates but levies an additional 1 percentage point tax on net investment income exceeding $1 million; and Washington imposes a 7 percent rate on capital gains income up to $1 million and an additional 2.9 percent excise taxAn excise tax is a tax imposed on a specific good or activity. Excise taxes are commonly levied on cigarettes, alcoholic beverages, soda, gasoline, insurance premiums, amusement activities, and betting, and typically make up a relatively small and volatile portion of state and local and, to a lesser extent, federal tax collections. on capital gains income over $1 million.
Eight states, like the federal government, apply lower effective individual income taxAn individual income tax (or personal income tax) is levied on the wages, salaries, investments, or other forms of income an individual or household earns. The U.S. imposes a progressive income tax where rates increase with income. The Federal Income Tax was established in 1913 with the ratification of the 16th Amendment. Though barely 100 years old, individual income taxes are the largest source rates to long-term gains than to ordinary income, either by applying lower statutory rates or by offering an exclusion for a portion of otherwise taxable capital gains, while Missouri exempts capital gains from its income tax. Eight states avoid this dilemma by forgoing an individual income tax altogether.
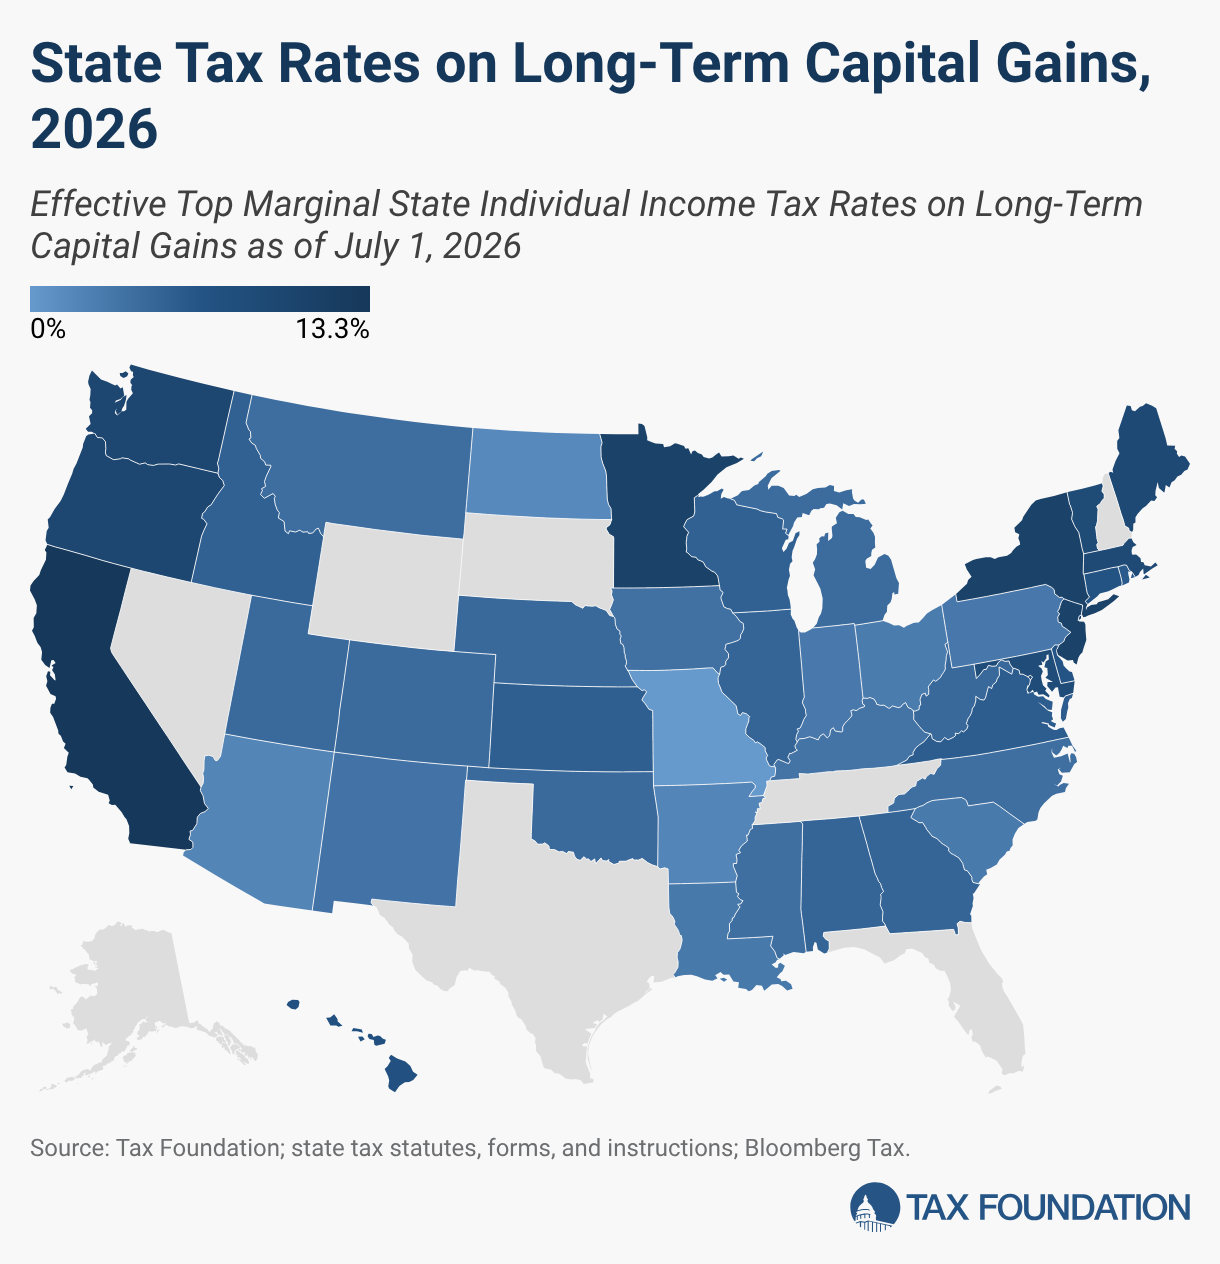
Twelve States Tax Capital Gains Income Differently Than Ordinary Income
State Top Marginal Tax Rates on Ordinary Income and Effective Top Marginal Rates on Long-Term Capital Gains Income as of January 1, 2026
| States Taxing Capital Gains at Lower Rates Than Ordinary Income | ||
|---|---|---|
| State | Top Marginal Rate on Ordinary Income | Effective Top Marginal Rate on Long-Term Capital Gains Income |
| Arizona (a, b) | 2.5% | 1.875% |
| Arkansas (a, c) | 3.7% | 1.85% |
| Hawaii (d) | 11% | 7.25% |
| Missouri (d, e) | 5% | n/a |
| Montana (d) | 5.7% | 4.1% |
| New Mexico (f) | 5.90% | 3.54% |
| North Dakota (a, g) | 2.5% | 1.5% |
| South Carolina (a, h) | 5.21% | 2.9176% |
| Wisconsin (a, i) | 7.65% | 5.355% |
| States Taxing Capital Gains at Higher Rates Than Ordinary Income | ||
| State | Top Marginal Rate on Ordinary Income | Effective Top Marginal Rate on Long-Term Capital Gains Income |
| Maryland (j) | 6.50% | 8.50% |
| Minnesota (k) | 9.85% | 10.85% |
| Washington (d, l) | 0% | 9.9% |
(a) State taxes capital gains income at a set percentage of the rate that applies to ordinary income.
(b) Arizona excludes 25 percent of net long-term capital gains, with the remainder taxed at ordinary rates.
(c) Arkansas excludes 50 percent of net long-term capital gains, with the remainder taxed at ordinary rates. The amount of a net gain that exceeds $10 million is exempt.
(d) Statutory top marginal tax rate for long-term capital gains income differs from rate for ordinary income.
(e) Missouri repealed its tax on capital gains as of January 1, 2025.
(f) New Mexico currently excludes the greater of $2,500 or 40 percent of up to $1 million of a taxpayer's net long-term capital gains from the sale of a New Mexico business. The $2,500 exemption applies to capital gains income broadly, while the 40 percent exclusion has been newly limited, effective as of 2025, to apply only to gains from the sale of a New Mexico business.
(g) North Dakota offers a 40 percent exclusion.
(h) South Carolina excludes 44 percent of net long-term capital gains.
(i) Wisconsin allows a 30 percent deduction on net long-term capital gains and a 60 percent deduction for farm assets.
(j) Maryland adds an additional 2% surtax for income exceeding $350,000.
(k) Minnesota's 10.85 percent top marginal effective rate on capital gains income includes a 1 percent tax on net investment income exceeding $1 million.
(l) In Washington, the first $1 million in taxable capital gains is subject to a tax rate of 7%. Any amount exceeding $1M is subject to a 2.9% excise tax. A standard deduction of $250,000 (regardless of filling status and indexed annually for inflation) is allowed before the 7 percent rate applies. Some types of capital gains income are excluded from taxation.
Sources: Tax Foundation research; state statutes, forms, and instructions; Bloomberg Tax.
Data compiled by Nicole Fox, Cole Kellison
It is worth noting that several states provide targeted preferential tax treatment for certain types of capital gains, often providing exemptions for qualifying capital gains from investments in certain industries. For example, Colorado offers a subtraction of up to $100,000 to farmers for capital gains from sales of qualifying agricultural real property, while Maine offers a subtraction to certain housing organizations for a portion of capital gains from the transfer of certain properties to be used for affordable housing. While these types of provisions vary considerably from state to state, their existence indicates that policymakers recognize that taxing capital gains the same as ordinary income can disincentivize investment and create economic distortions. However, these provisions are often very narrowly targeted, offering tax advantages to only a small subset of taxpayers.
At the state level, taxing long-term capital gains at lower rates or excluding a set percentage of capital gains income (for all taxpayers and for all types of capital gains) helps offset the fact that capital gains taxes apply to nominal, not real, capital gains. Therefore, more states should reconsider their treatment of long-term capital gains, either by applying a lower statutory rate to capital gains income or excluding a certain percentage of otherwise taxable capital gains. Additionally, states should also ensure they provide robust and timely deductions for capital losses.
Even when lower rate schedules or exclusions are granted, capital gains taxes represent a form of double taxationDouble taxation is when taxes are paid twice on the same dollar of income, regardless of whether that’s corporate or individual income. on investment income. To illustrate this, consider an individual who decides to save for the future by purchasing shares of stock in a company. Unless the shares are purchased through tax-advantaged investment accounts—like a 401(k) or IRA, where invested income is taxed only once, either on the way in (Roth accounts) or on the way out (traditional accounts)—the investment is made using ordinary wage or salary income that has already been taxed under standard federal and state individual income tax rate schedules.
Under favorable circumstances, the value of that investment will grow over time. The growth reflects corporate earnings that have already been subject to corporate income taxes, reducing the amount of income ultimately distributed to investors. Years or decades later, when the investor sells their shares and realizes a capital gain, the same underlying income will be taxed again under the individual income tax.
While preferential rates applied to long-term capital gains reduce this burden, they do not eliminate it. Moreover, the burden can be compounded by the fact that capital gains are measured by nominal rather than inflation-adjusted dollars. Thus, taxpayers may owe tax not only on previously taxed earnings but also on inflationary gains that do not represent a real increase in purchasing power.
When evaluating the tax treatment of investment income, state policymakers should consider all layers of taxes on those earnings, including corporate income taxes, and understand how the failure to inflation-index the tax basis, combined with most states’ failure to adjust rates accordingly, results in the widespread overtaxation of capital gains income in the United States.
Savings and investment are essential for individuals’ and families’ financial security and for long-term economic growth. Policymakers should therefore consider reforms that can help mitigate—rather than add to—tax codes’ biases against saving and investment.
Stay informed on the tax policies impacting you.
Subscribe to our free newsletter to get the latest tax data, news and analysis.
Subscribe