2026 Spanish Regional Tax Competitiveness Index
The 2026 Spanish Regional Tax Competitiveness Index allows policymakers and taxpayers to evaluate and measure how their regions’ tax systems compare.
8 min read
Cristina Enache writes on the economics of tax policy and is the author of the Spanish Regional Tax Competitiveness Index. She was formerly the Director of Research at Civismo, an economic research organization based in Spain. She also served as head of research at Institución Futuro, a regional think tank based in Navarra in northern Spain. She is also currently Secretary-General at the World Taxpayers Associations and General Manager of the Spanish Taxpayers Union, which she joined in 2016.
Cristina has a degree in economics from the Academy of Economic Studies in Bucharest and a master’s degree in Economics and Finance from the University of Navarra.
The 2026 Spanish Regional Tax Competitiveness Index allows policymakers and taxpayers to evaluate and measure how their regions’ tax systems compare.
8 min read
On September 15th, Canada announced that full expensing for machinery, equipment, and patent rights will be made permanent and broadened from around 15 percent to two thirds of business capital investment.
6 min read
As energy prices have declined, European countries have switched the focus of their windfall profits taxes—a one-time tax levied on a company or industry when economic conditions result in large, unexpected profits—from energy providers to the banking and financial sector.
7 min read
The Belgian proposal departs significantly from sound tax policy principles and risks generating substantial economic distortions, legal uncertainty, and trade frictions while raising relatively little revenue.
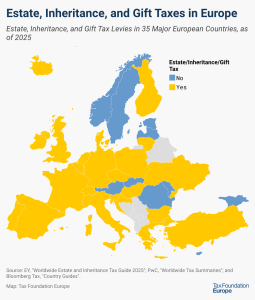
Twenty-four out of the 35 European countries covered in this map currently levy estate, inheritance, or gift taxes.
4 min read
If Canada doesn’t make these provisions permanent, it will drop to 12th place in the capital cost recovery ranking once provisions expire in 2034.
5 min read
Though they are often framed as affecting only the richest households, the economic effects of wealth taxes extend much further by reducing capital formation, discouraging entrepreneurship, curtailing wage and employment growth, and ultimately weakening the overall economy.
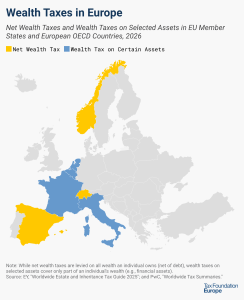
Wealth taxes not only collect little revenue and create legal uncertainty, but an OECD report argues that they can also disincentivize entrepreneurship, harming innovation and long-term growth.
5 min read
Rather than adopt temporary policies that phase out and expire, policymakers should focus their efforts on long-term reforms to support investment.
7 min read
The ongoing economic uncertainty from global geopolitical threats, supply chain disruptions, rising interest rates, and lagging economic growth in many developed countries have highlighted the importance of private business investment.
32 min read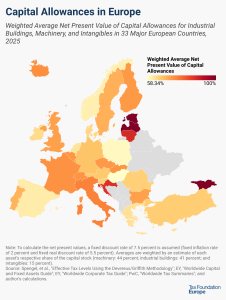
Although sometimes overlooked in discussions about corporate taxation, capital allowances play an important role in a country’s corporate tax base and can impact investment decisions—with far-reaching economic consequences.
6 min read
Digital services taxes address a real concern—the need to adapt taxation to the digital economy—but they are not the right solution. They raise limited revenue, are often passed on to consumers rather than large digital firms, create economic distortions, increase complexity and compliance costs, negatively impact innovation and competitiveness, and risk international retaliation.

Since digital services taxes generate little revenue, place the cost on European consumers and not on large digital companies as intended, and risk escalating trade disputes, policymakers should rethink their strategy.
14 min read
The Reform UK proposal to exempt overtime pay from income tax—framed as a “hard work bonus”—may be politically appealing, but it’s a flawed idea that undermines economic fairness, distorts labor markets, and jeopardizes tax revenues.
4 min read
Currently, about half of all European OECD countries have either announced, proposed, or implemented a digital services tax. Because these taxes mainly impact US companies and are thus perceived as discriminatory, the US responded with retaliatory tariff threats.
5 min read
Windfall taxes, particularly those imposed on the oil and gas industry, often appear as a quick fix for governments seeking to raise revenue during periods of high commodity prices. However, while these taxes may offer short-term revenues, they can also trigger negative consequences that undermine their intended purpose.
21 min read
Closing the EU’s value-added tax (VAT) actionable policy gap could yield €773 billion in government revenue—four times the EU’s 2026 budget.
8 min read
Many countries’ personal income tax systems tax various sources of individual income—including investment income such as dividends and capital gains.
4 min read
Poland is proposing to broaden and raise its digital services tax (DST) from 1.5 percent to 3 percent. Because DSTs tax revenues, not profits, a company with a 10 percent profit margin would face a 30 percent effective tax rate on digital services provided in Poland.
6 min read
The value-added tax (VAT) compliance gap—the additional VAT revenue that could be collected if all taxpayers, consumers, and businesses fully complied with VAT rules—continues to increase, reaching €128 billion in 2023.
8 min read