Skip to content

Taxes In Oklahoma

2026 Oklahoma Tax Rates, Collections, and Burdens

How Do Oklahoma Taxes Compare to Other States?

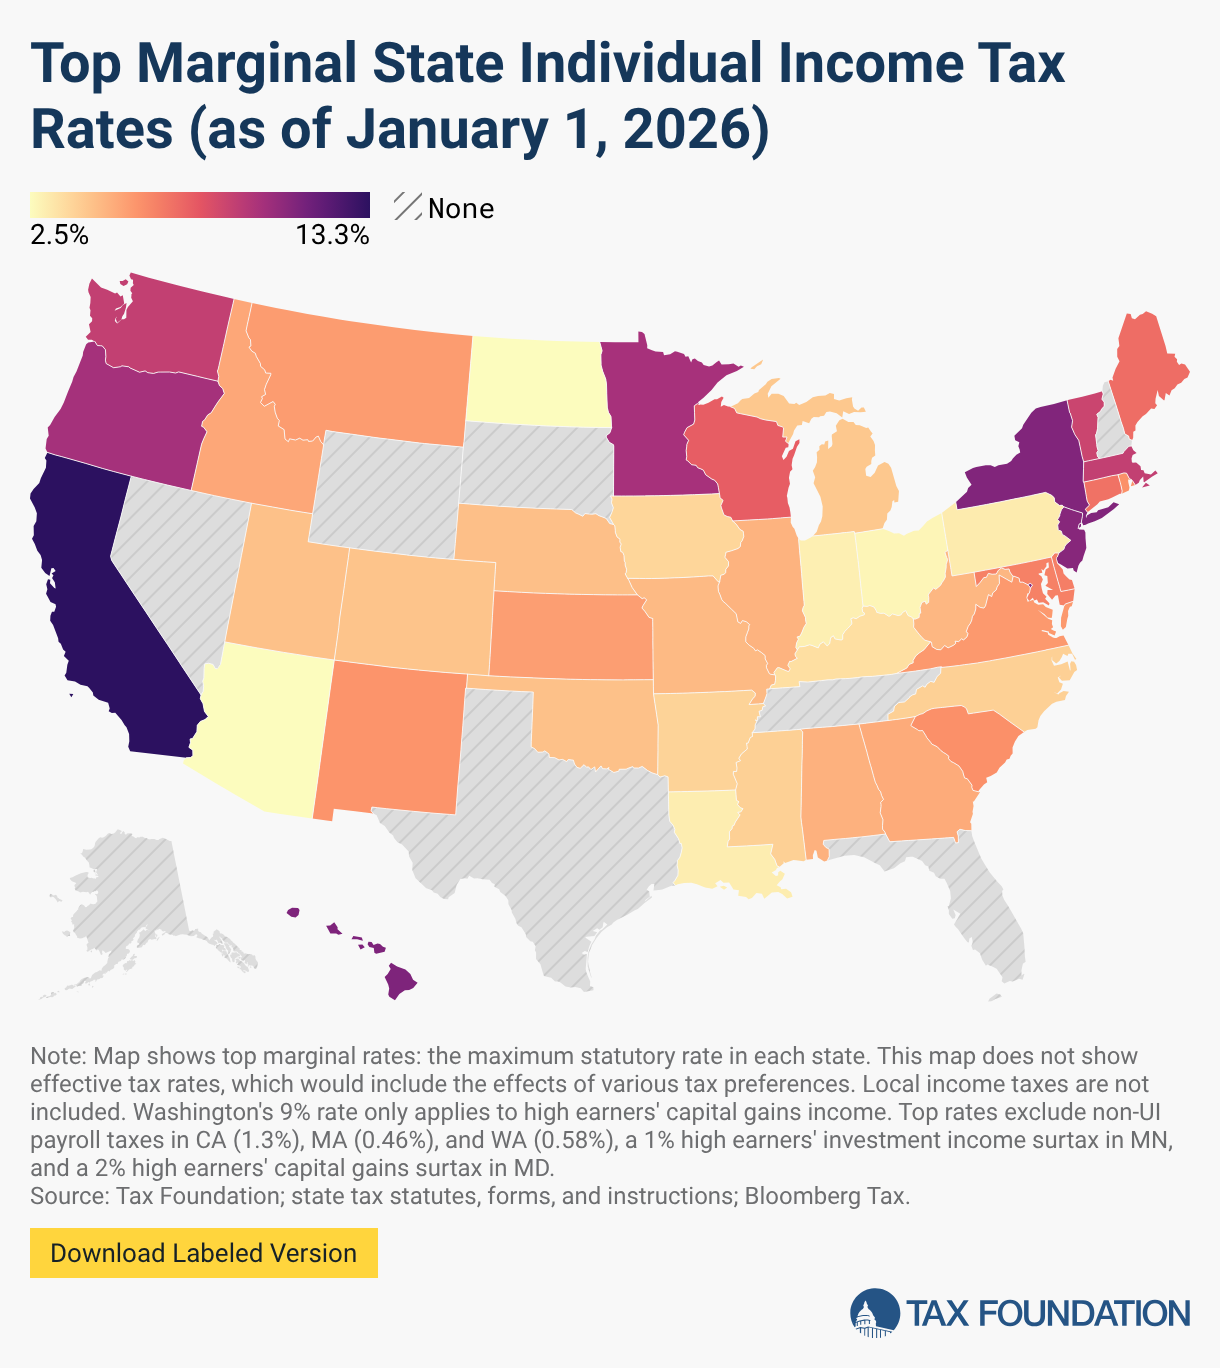
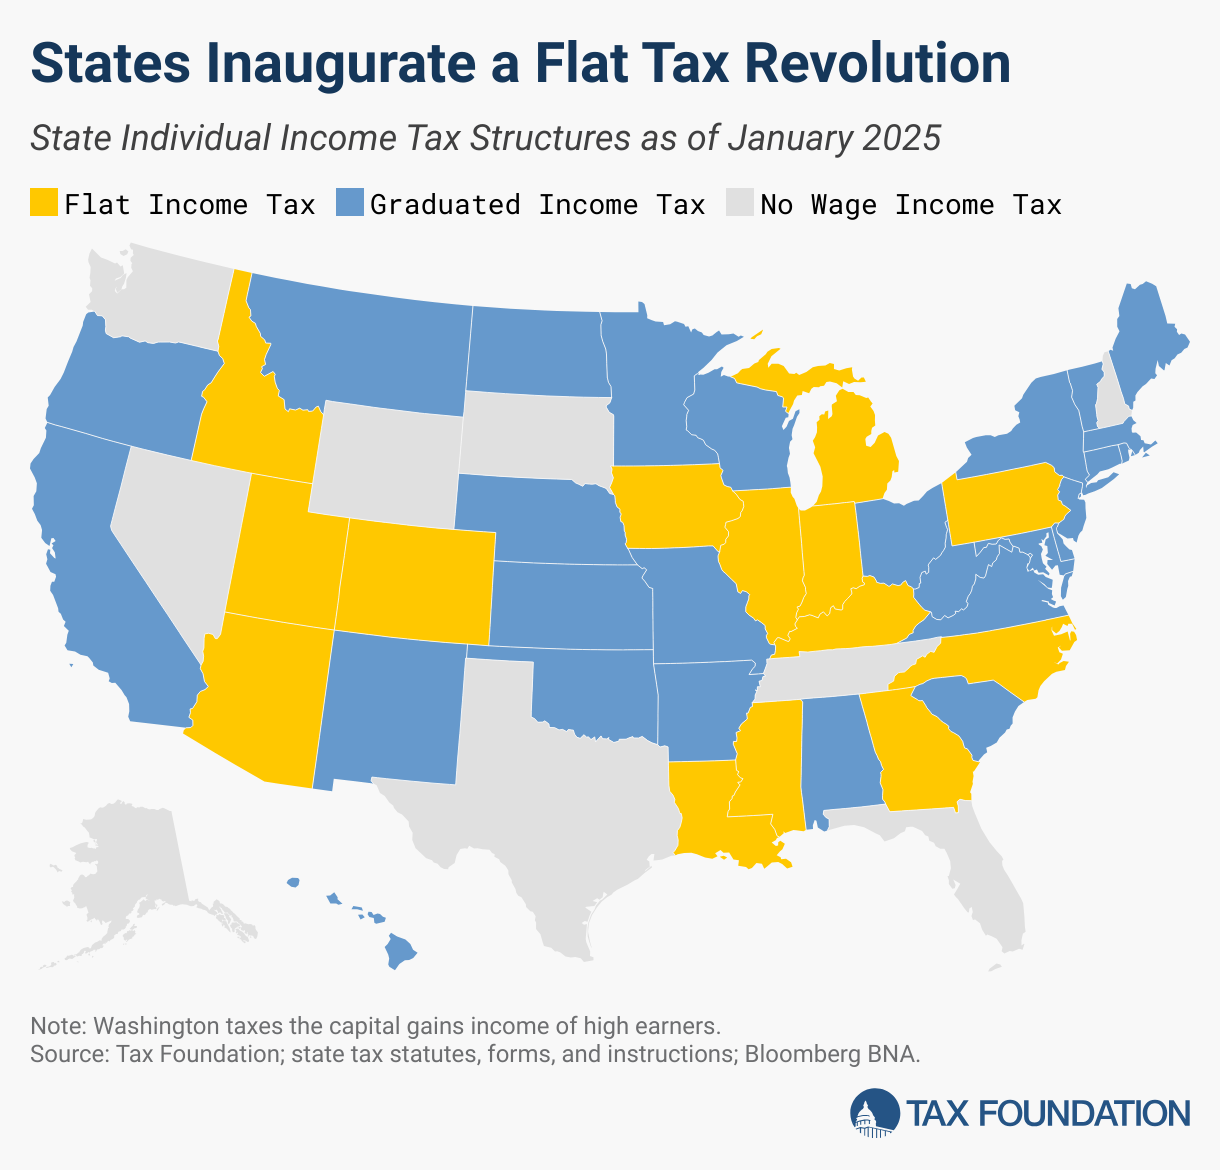
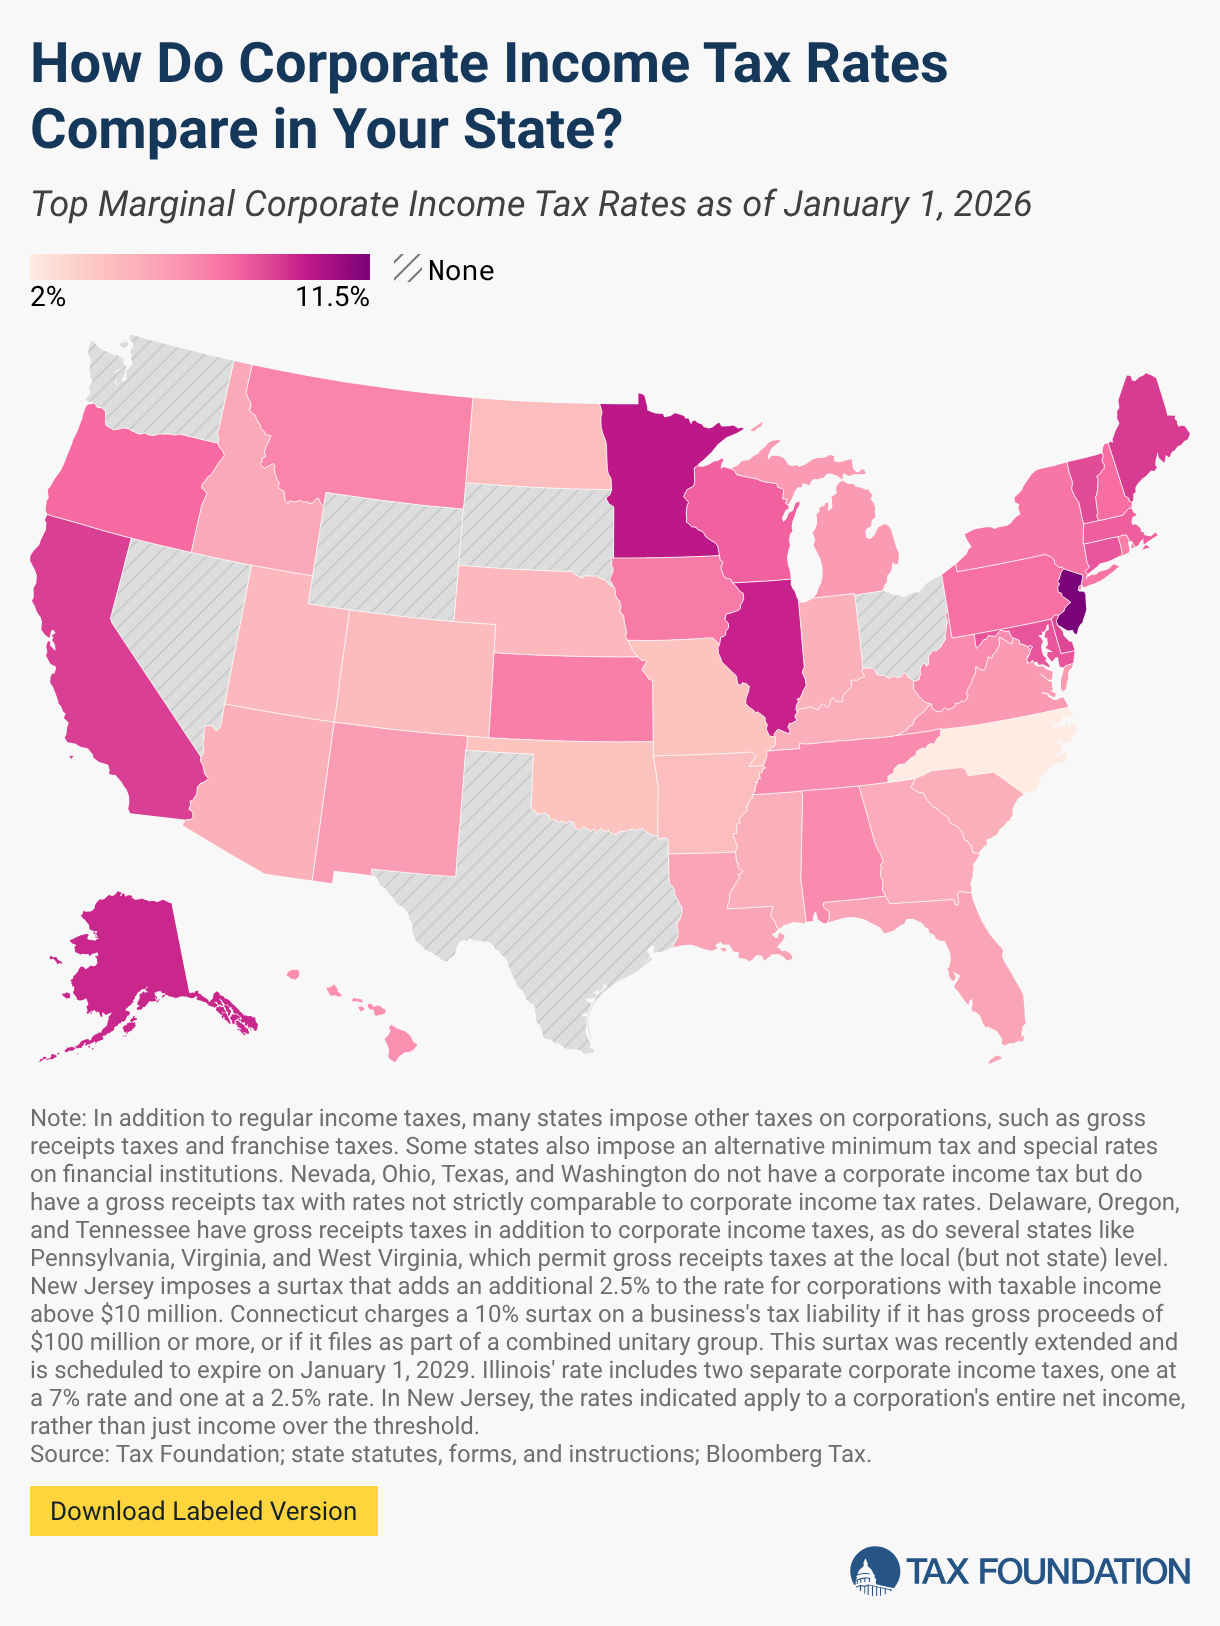
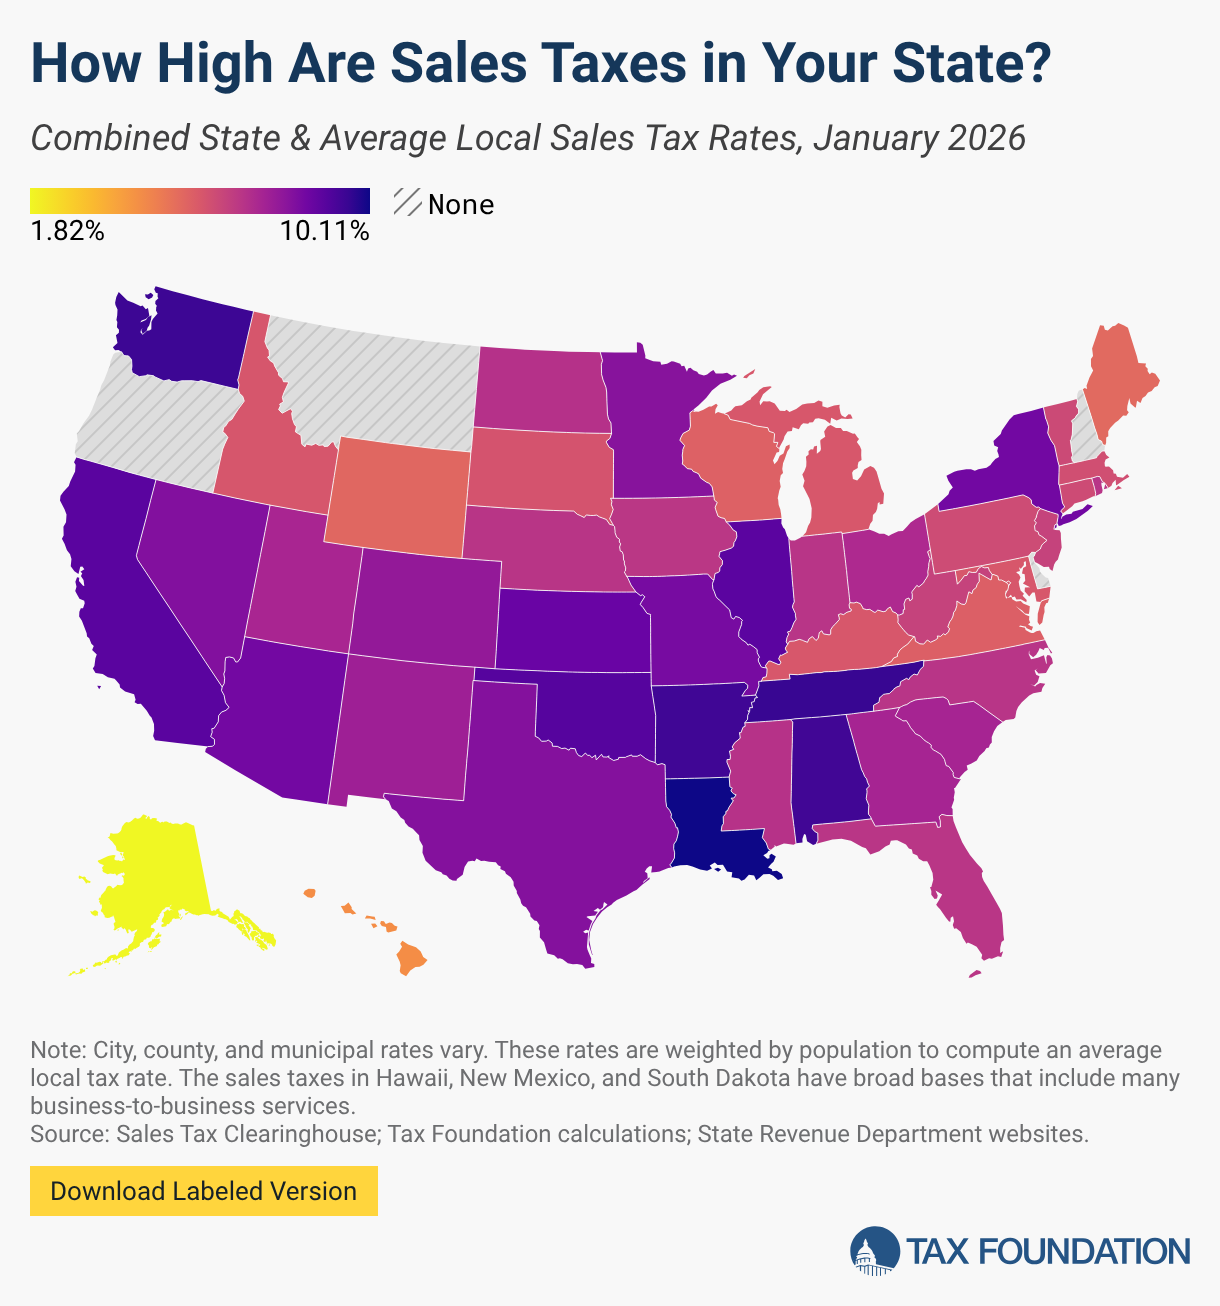
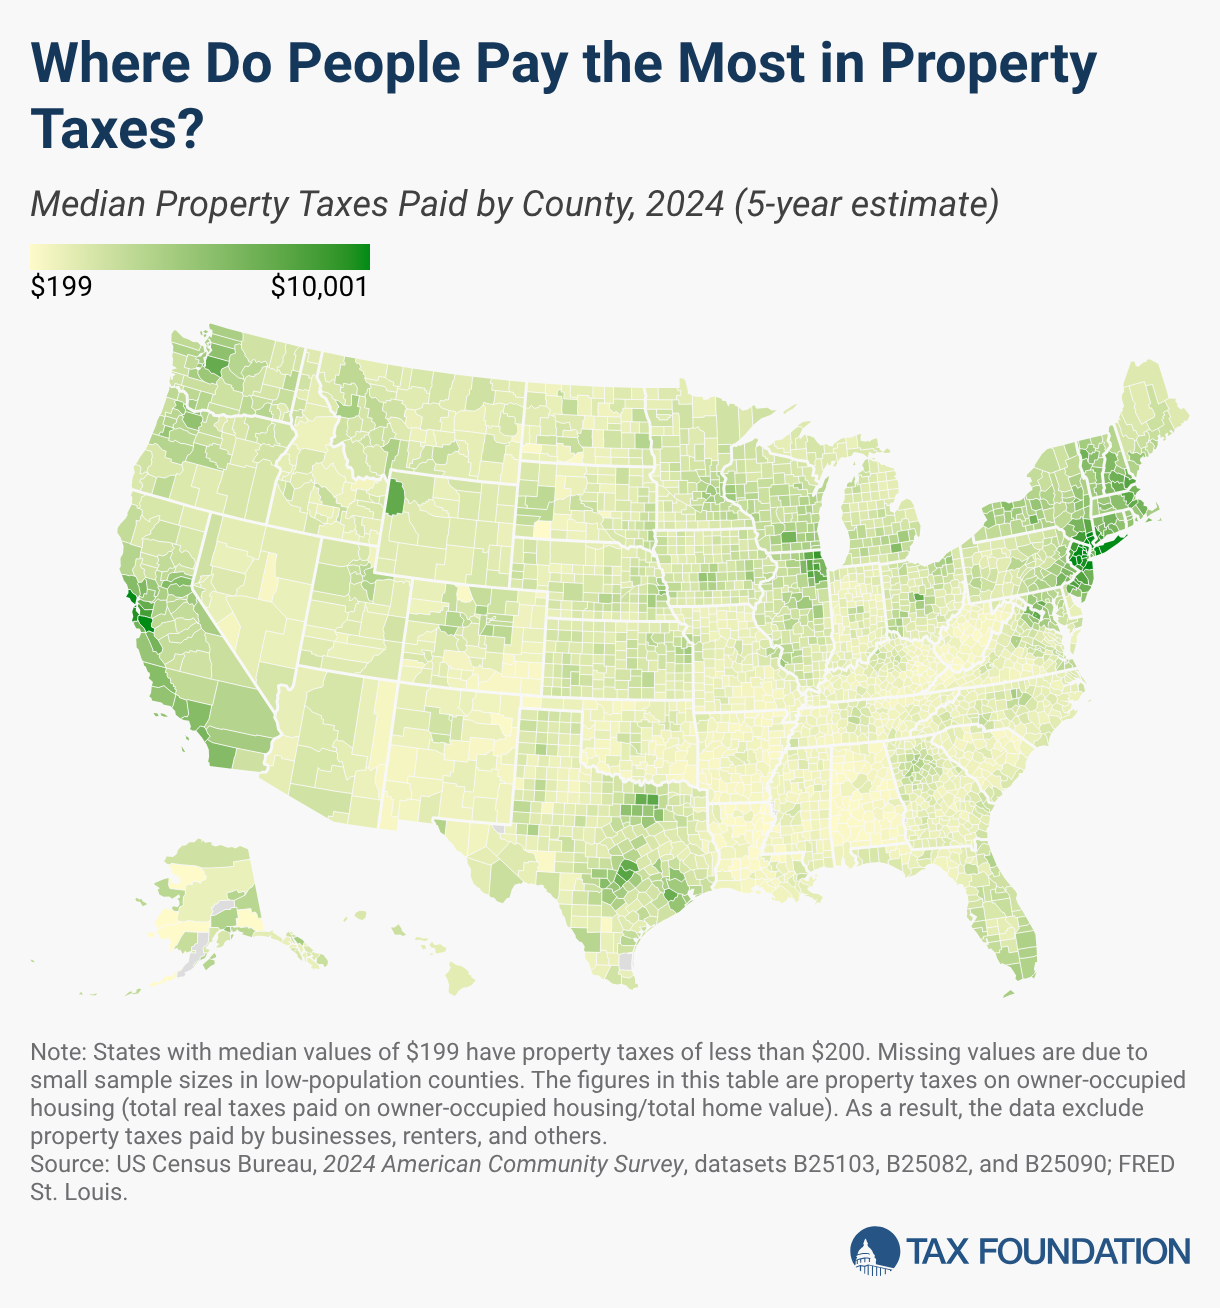
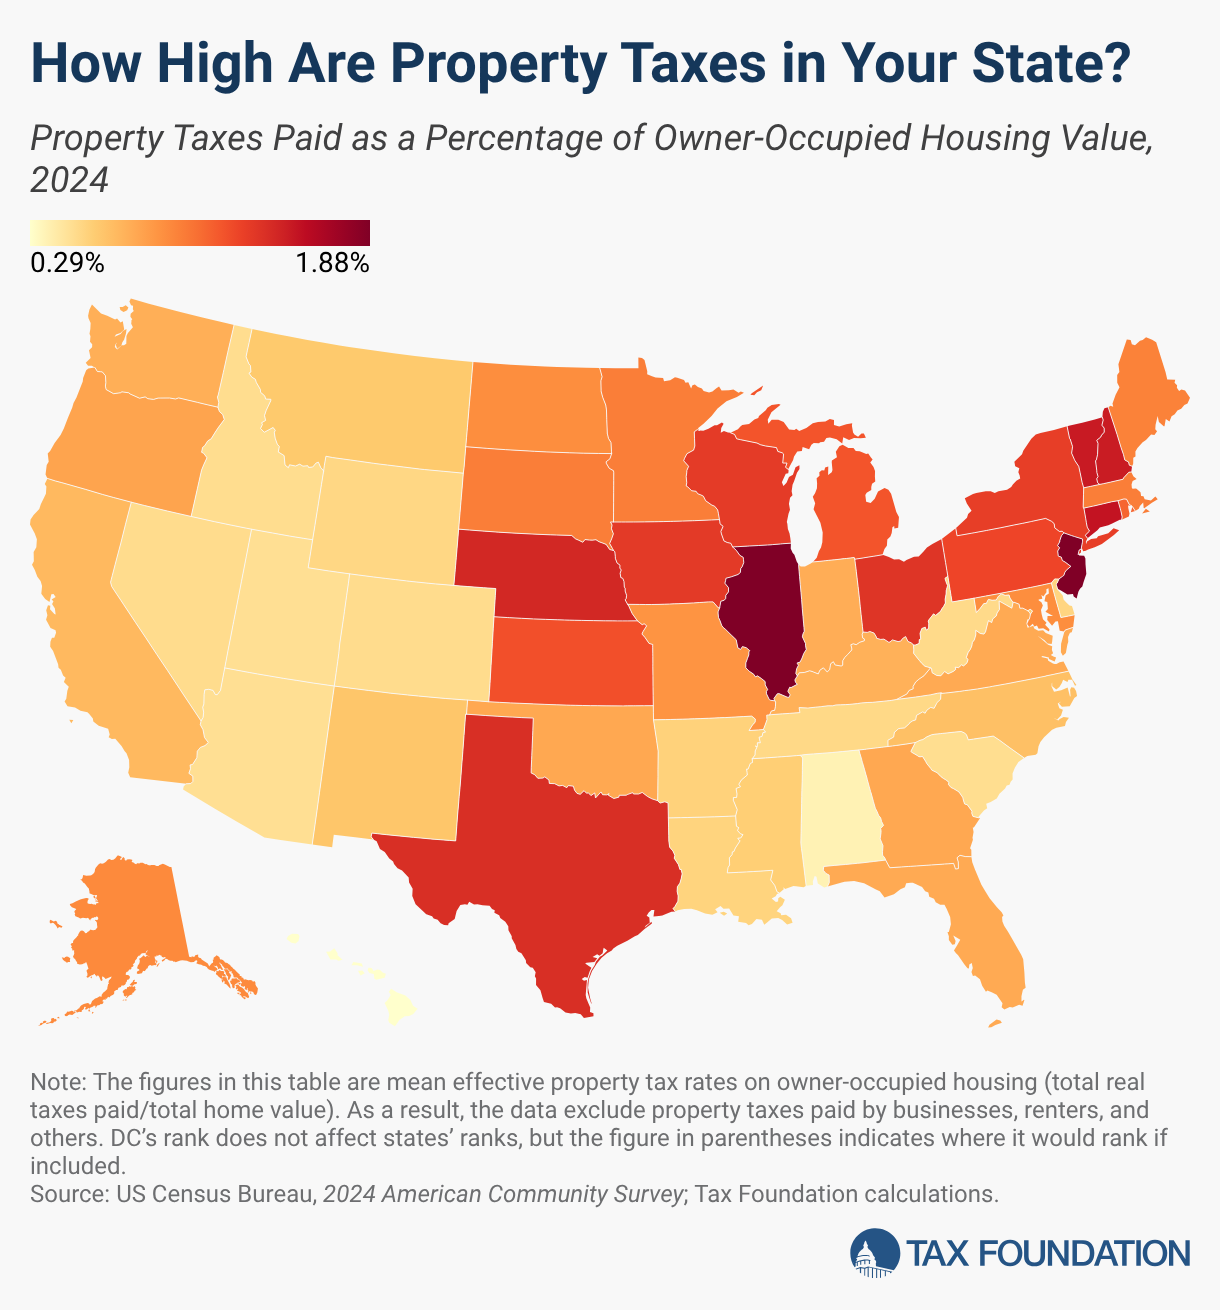
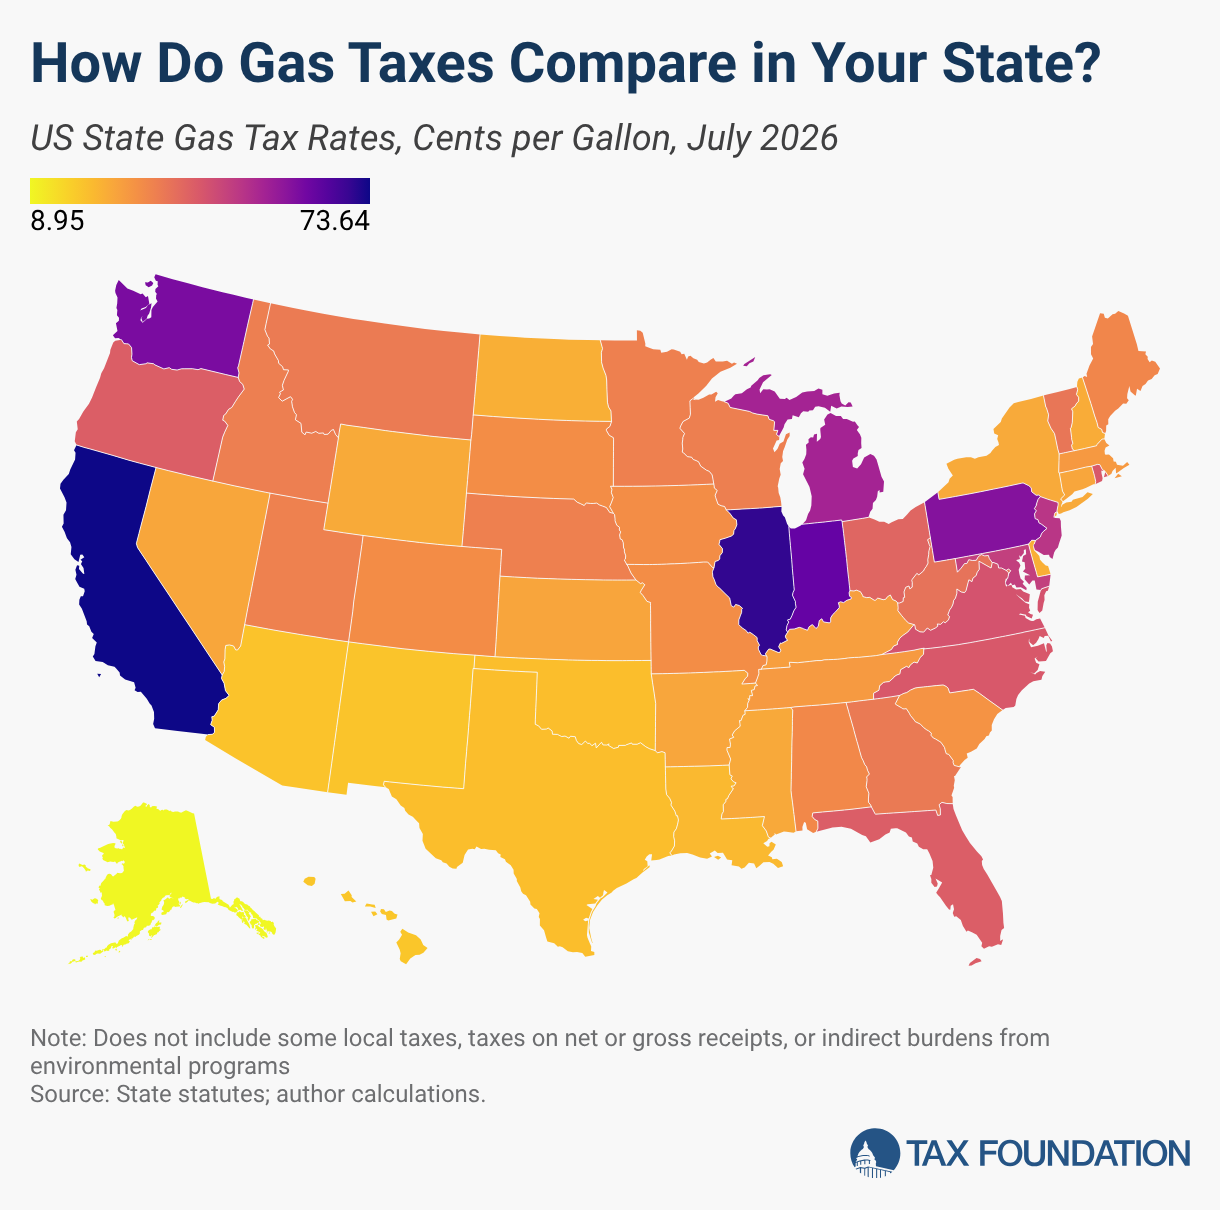
Oklahoma has a graduated state individual income tax with three brackets and rates ranging from 0.50 percent to 4.50 percent. Oklahoma has a flat 4.00 percent corporate income tax rate, a 4.50 percent state sales tax rate, and an average combined state and local sales tax rate of 8.99 percent. Oklahoma has a 0.79 percent effective property tax rate on owner-occupied housing value. Oklahoma does not have an estate tax or inheritance tax. Oklahoma’s gas tax is 20 cents per gallon, and its cigarette excise tax is $2.03 per pack of 20 cigarettes.

Oklahoma Tax Rankings, Debt, and Tax Revenue

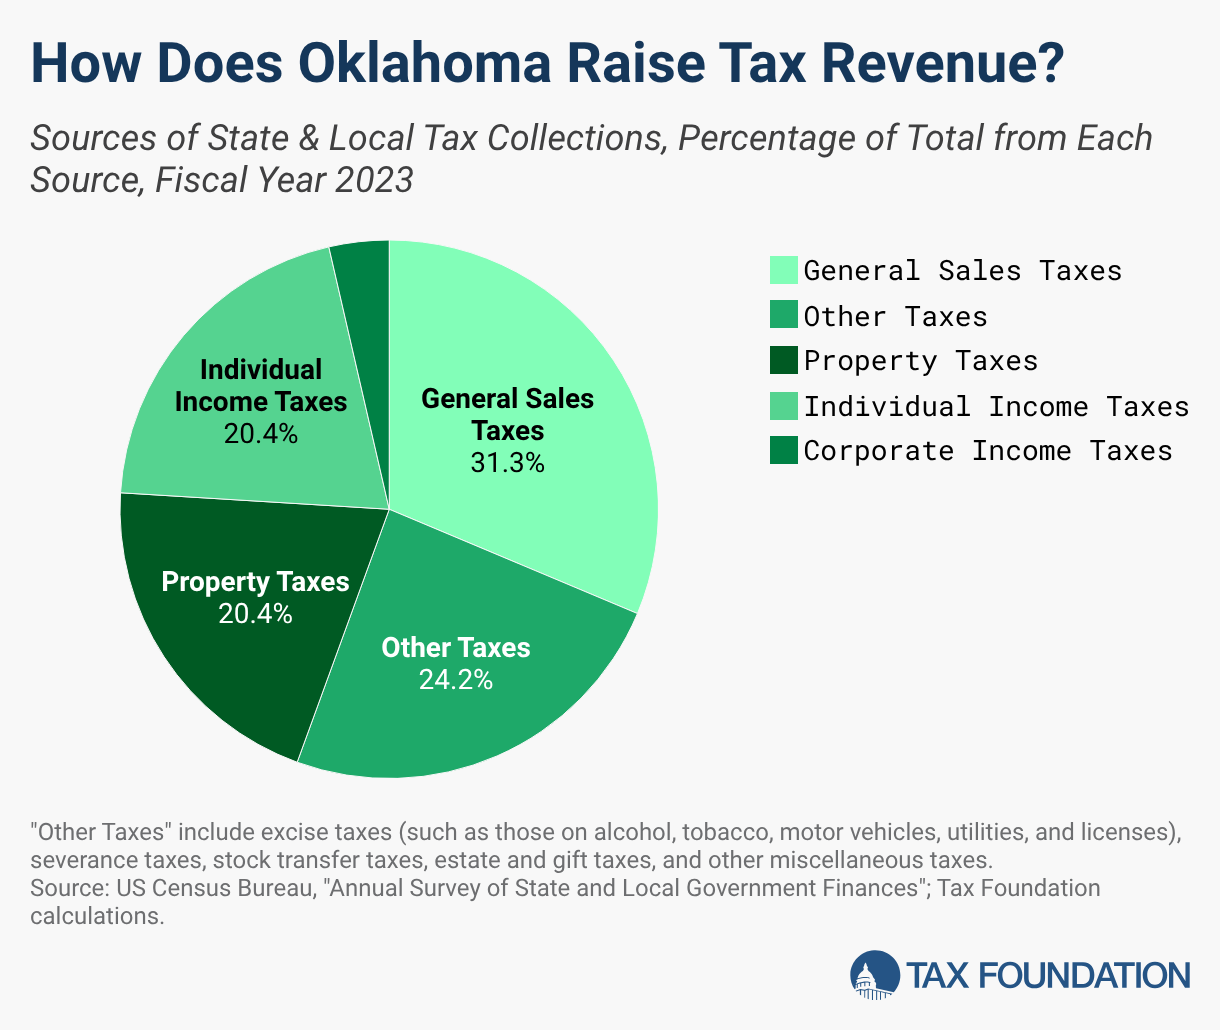
Oklahoma raises tax revenue primarily through general sales taxes (31.3 percent of total state and local tax revenue), other taxes (24.2 percent), and individual income taxes (20.4 percent). Oklahoma collects $5,312 in state and local tax collections per capita, carries $5,340 in state and local debt per capita, and has a 90 percent funded ratio of public pension plans. Oklahoma’s tax system ranks 15th overall on the 2027 State Tax Competitiveness Index.

Understanding Oklahoma’s Tax System

Each state’s tax code is a multifaceted system with many moving parts, and Oklahoma is no exception. Use the tabs below to compare Oklahoma taxes with other states and to see how Oklahoma raises tax revenue. You can also browse our tax maps, which are compiled from our annual publication, Facts & Figures 2026: How Does Your State Compare?

See Related Articles

Tax Data by State

Get facts about taxes in your state and around the US

Explore Data

How Do Taxes in Oklahoma Compare?

How Does Oklahoma Collect Revenue?

How Does Oklahoma's Tax System Rank?


All Related Articles

2027 State Tax Competitiveness Index Interactive Tool 2027 State Tax Index

2027 State Tax Competitiveness Index

The State Tax Competitiveness Index enables policymakers, taxpayers, and business leaders to gauge how their states’ tax systems compare. While there are many ways to show how much state governments collect in taxes, the Index evaluates how well states structure their tax systems and provides a road map for improvement.

121 min read
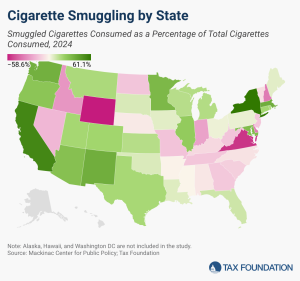
Cigarette Taxes and Cigarette Smuggling by State

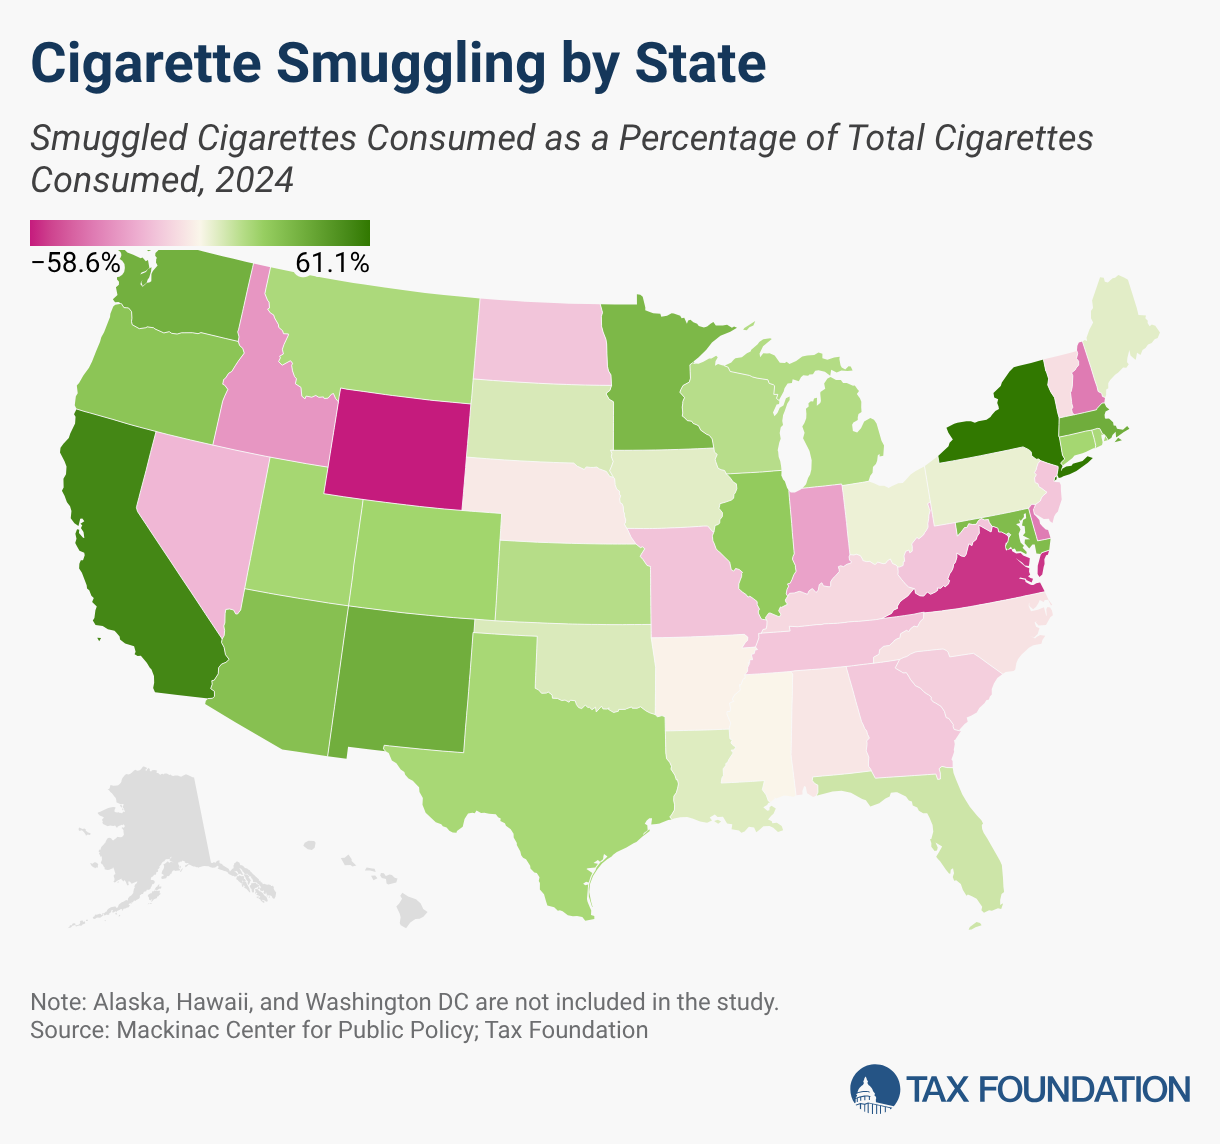
Cigarette Taxes and Cigarette Smuggling by State, 2024

Cigarette smuggling is costly for states. We estimate that the forgone revenue from smuggled cigarettes totaled more than $4.6 billion in 2024. California lost nearly $1.4 billion in cigarette excise tax collections, and New York missed out on more than $1.2 billion.

5 min read
Modernizing Rental Car and Peer-to-Peer Car Sharing Taxes for a Post-Pandemic Future

Rental Cars Shouldn’t Face Another Layer of Tax

Imposing sales taxes on rental car companies’ fleet purchases, in addition to the sales and rental car excise taxes levied when those cars are rented, yields double taxation and causes harmful tax pyramiding.

9 min read
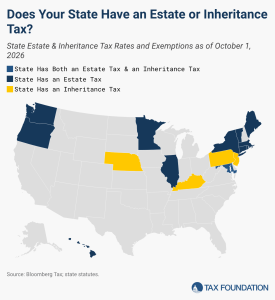
Estate and Inheritance Taxes by State, 2026

Estate and Inheritance Taxes by State, 2026

In addition to the federal estate tax, which has a top marginal rate of 40 percent, 12 states and the District of Columbia impose estate taxes, while five states levy inheritance taxes.

8 min read
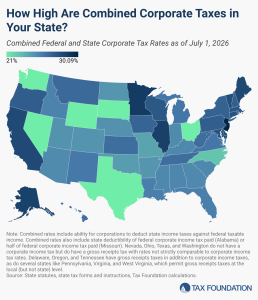
Combined state and federal corporate tax rates as of 2026

Combined State and Federal Corporate Income Tax Rates in 2026

Corporations in the United States pay federal corporate income taxes levied at a 21 percent rate. Forty-four states and DC also levy taxes on corporate income, with top marginal rates ranging from 2.5 percent in North Carolina to 11.5 percent in New Jersey.

2 min read
Real Property Taxes in Europe, 2026

Real Property Taxes in Europe, 2026

High property taxes levied not only on land but also on buildings and structures can discourage investment in infrastructure, which businesses would have to pay additional tax on.

3 min read
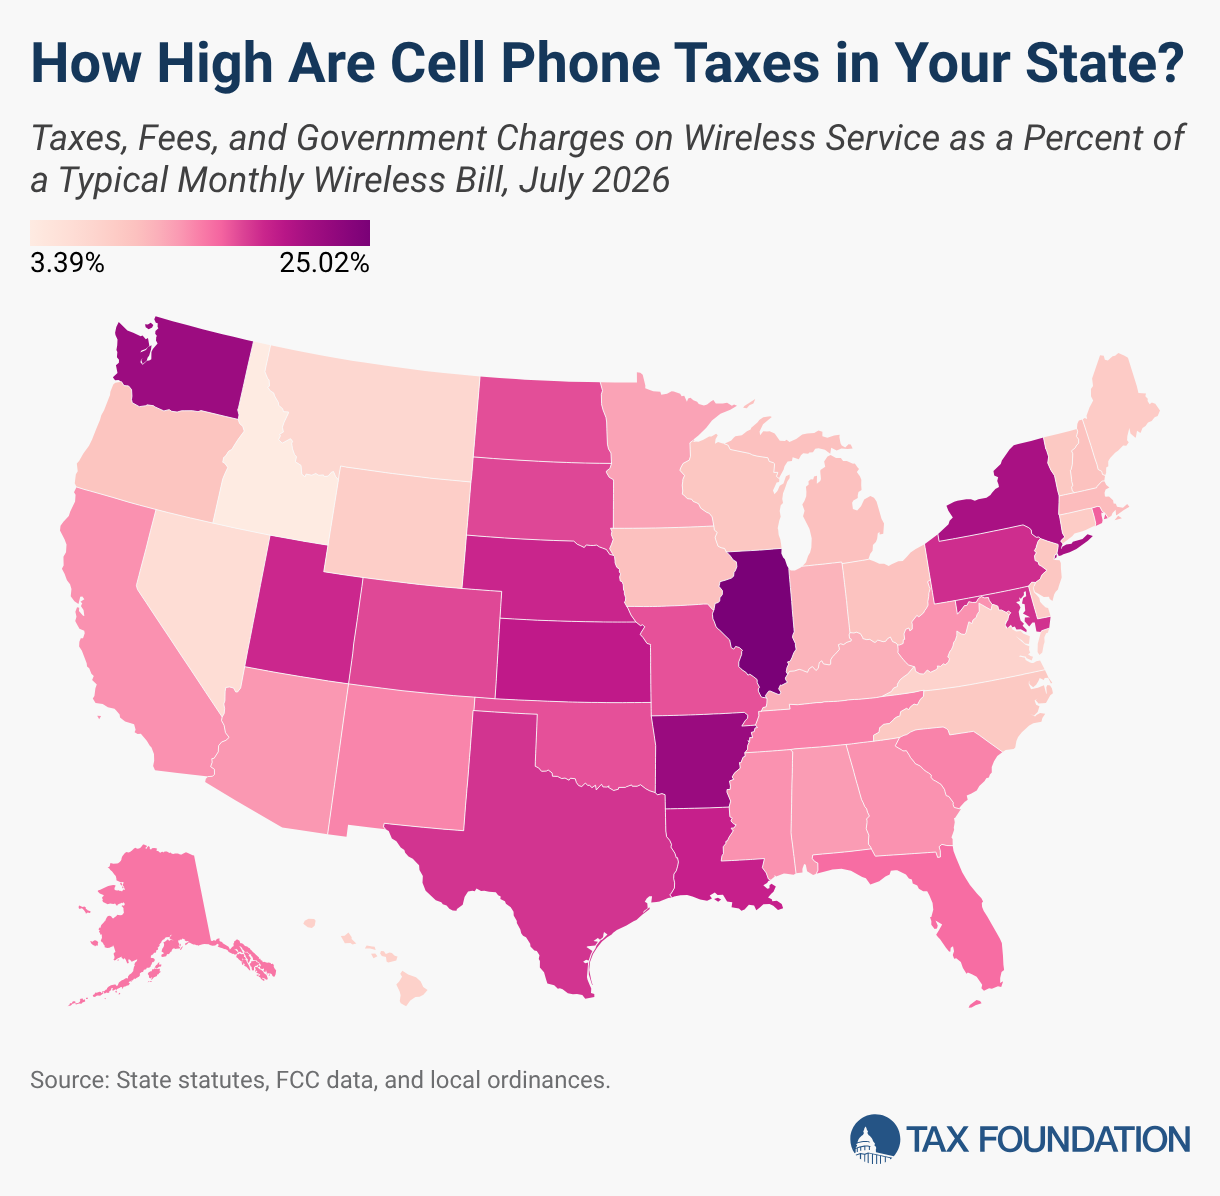
Wireless Cell Phone Taxes by State, 2026

Federal Surcharge Drives Another Increase in Wireless Taxes and Fees in 2026

Applying the sales tax, a traditional broad-based consumption tax, is perfectly appropriate, but excessive targeted taxation of wireless services lacks the traditional justifications—a user-pays system or the internalization of social costs—for excise taxation, raising consumer costs and discouraging investment.

5 min read