Skip to content

100 Percent Bonus Depreciation (Full Expensing)

Studies show that when bonus depreciation is available, businesses respond by investing in more equipment and increasing employment, as they need more workers to operate the new equipment.

Download Expensing Primer  Learn more with TaxEDU

All Related Articles

Corporate tax reform analysis including corporate tax hike economic growth impact

Three Facts Straightening Out the Debate Over Bonus Depreciation

Expensing for capital investment is not a special tax break. Expensing aligns the timing of tax deductions with the timing of actual capital expenditures so that the tax code does not discourage marginal investment projects. 

7 min read
Canada Full Expensing Made Permanent, Capital Investment and Cost Recovery

Full Expensing to Be Made Permanent in Canada

On September 15th, Canada announced that full expensing for machinery, equipment, and patent rights will be made permanent and broadened from around 15 percent to two thirds of business capital investment.

6 min read

The Five Most Pro-Growth Options in the Options Guide

Some taxes have more powerful economic effects than others, and that’s a lesson policymakers should absorb as they work to craft a tax code that encourages growth and raises sustainable revenue.

8 min read
OECD Capital Cost Recover, 2026

Capital Cost Recovery across the OECD, 2026 Update

The ongoing economic uncertainty from global geopolitical threats, supply chain disruptions, rising interest rates, and lagging economic growth in many developed countries have highlighted the importance of private business investment.

32 min read
2026 capital allowances europe expensing and cost recovery policies to encourage capital investment

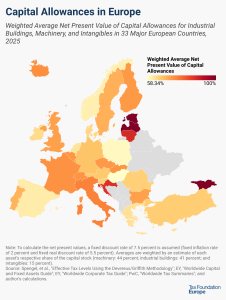
Capital Allowances in Europe, 2026

Although sometimes overlooked in discussions about corporate taxation, capital allowances play an important role in a country’s corporate tax base and can impact investment decisions—with far-reaching economic consequences.

6 min read
Foreign Research and Development, OBBBA Full Expensing

The Hidden Costs of Foreign R&D Amortization

Foreign R&D generally complements domestic innovation rather than substituting for it, so penalizing foreign R&D weakens US firms in cross-border mergers and acquisitions and in domestic production that depends on global scale.

7 min read
full expensing tariffs trump big beautiful bill no The Low-Tax Case for Tariffs

There Is No Low-Tax Case for Tariffs

Full expensing under the One Big Beautiful Bill Act does not neutralize the tariff burden on imported goods, as former White House Council of Economic Advisers chair Stephen Miran asserts.

8 min read
company disclosure; company tax disclosure tax disclosure tax transparency country by country reporting cbcr

Three Questions to Ask About New Tax Transparency Regimes

The new data disclosures will draw significant attention in 2026 and beyond. However, because the data is rooted in financial accounting concepts, affected by timing issues, and shaped by inconsistent reporting regimes, it is poorly suited for drawing strong conclusions about tax policy or corporate behavior.

7 min read
Windfall Profits Taxes on Oil and Gas in Europe

Windfall Profits Taxes on Oil and Gas Should Be Left in the Past

Windfall taxes, particularly those imposed on the oil and gas industry, often appear as a quick fix for governments seeking to raise revenue during periods of high commodity prices. However, while these taxes may offer short-term revenues, they can also trigger negative consequences that undermine their intended purpose.

21 min read
We are living in an age of hyperbole, or as writer Matthew Hennessey calls it, the “Age of Excusability,” in which our politicians succeed by making outlandish claims. So it goes with the One Big Beautiful Bill, which will usher in a new golden age or send us down the tubes for good, depending on your sources.

Testimony: The Impact of the 2025 Reconciliation Law’s Tax Changes on Small Businesses and Lessons for Future Tax Reform

Policymakers should broaden and make permanent full expensing for additional asset classes and pursue structural reforms that reduce distortions in how businesses are taxed. A more consistent and predictable policy environment, paired with targeted improvements to loss treatment, R&D incentives, and compliance burdens, would give small business owners greater confidence to invest, hire, and grow.