A “Token Tax” Could Kill the Promise of AI
If we want to ensure that AI raises economic growth, we shouldn’t be pursuing tax policies that are stuck in the past and represent some of the worst ideas from the early internet age.

Garrett Watson is Vice President of Federal Tax Policy with Tax Foundation’s Center for Federal Tax Policy. His work has been featured in The Washington Post, The Atlantic, Politico, the Associated Press and other major outlets.
Previously, Garrett was a program manager at a nearby think tank and conducted policy research on economic opportunity and labor markets, including non-compete clause reform.
Garrett earned a bachelor’s degree from St. Lawrence University in upstate New York, where he studied economics and philosophy. Garrett lives in northwest Arkansas and is an avid hockey fan and snowboarder.
If we want to ensure that AI raises economic growth, we shouldn’t be pursuing tax policies that are stuck in the past and represent some of the worst ideas from the early internet age.
Nearly half of all hospitals are exempt from paying US corporate income taxes. As healthcare spending rises, lawmakers have questioned whether hospitals are providing as much in community benefits as they derive from tax exemptions.
11 min read
Hall’s research helped economists understand how taxes distort investment decisions, while his work with Rabushka shows how to minimize those distortions. Although the US remains far from a pure consumption tax, Hall’s work informs efforts to reduce the tax burden on investment, improve neutrality, and promote long-run economic growth.
3 min read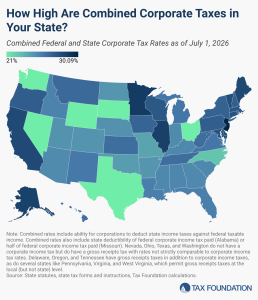
Corporations in the United States pay federal corporate income taxes levied at a 21 percent rate. Forty-four states and DC also levy taxes on corporate income, with top marginal rates ranging from 2.5 percent in North Carolina to 11.5 percent in New Jersey.
2 min read
The proposed GROWTH Act would make the tax treatment of investment funds more consistent and improve the tax treatment of saving in the US by allowing investors to defer tax on qualifying reinvested capital gains distributions until they sell their fund shares.
6 min read
Expensing for capital investment is not a special tax break. Expensing aligns the timing of tax deductions with the timing of actual capital expenditures so that the tax code does not discourage marginal investment projects.
7 min read
The “no tax on” deductions show the drawbacks of using narrowly tailored provisions to provide tax relief.
6 min read
Investment in digital assets, long thought of as a niche interest reserved for enthusiasts, has broken into the mainstream. In 2026, about one in five US adults report being invested in or using cryptocurrency.
5 min read
US policymakers have put forward two new tax proposals to address concerns about how artificial intelligence (AI) will impact land, energy, and the workforce.
7 min read
The Tax Foundation uses and maintains a General Equilibrium Model, known as our Taxes and Growth (TAG) Model to simulate the effects of government tax and spending policies on the economy and on government revenues and budgets.
9 min read
In 2022, incomes for the bottom 80 percent of earners were slightly lower after taxes and transfers compared to 2020 and 2021, driven by expiring pandemic-era policies.
6 min read
Policymakers should broaden and make permanent full expensing for additional asset classes and pursue structural reforms that reduce distortions in how businesses are taxed. A more consistent and predictable policy environment, paired with targeted improvements to loss treatment, R&D incentives, and compliance burdens, would give small business owners greater confidence to invest, hire, and grow.

As the policy debate for the next presidential election begins to take shape, both sides need to be honest about their plans for addressing the actual challenges our country faces.

Senators Chris Van Hollen (D-MD) and Cory Booker (D-NJ) have each introduced proposals aimed at cutting taxes for lower- and middle-income taxpayers and raising them on high-income taxpayers.
9 min read
 Short Form
If you’ve filed your taxes already, you may have noticed a larger refund this year. That’s due to changes Congress made with the One Big Beautiful Bill Act (OBBBA) last year that retroactively cut taxes for 2025.
3 min read
Senator Bernie Sanders introduced a proposed 5 percent annual wealth tax on billionaires to fund direct payments to Americans and expand social welfare programs.
5 min read
Notably, the OBBBA makes permanent the individual tax changes first put in place by the TCJA, which avoids a tax hike on an estimated 62 percent of tax filers in 2026.
4 min read
Our analysis of the major tax provisions included in the OBBBA finds it will increase long-run GDP by 0.7 percent. The major tax provisions will reduce federal tax revenue by nearly $5.2 trillion between 2025 and 2034, on a conventional basis.
12 min read
When taxpayers file their 2025 tax returns in 2026, many will see larger refunds than in recent years. That’s due to the One Big Beautiful Bill Act (OBBBA), which reduced individual income taxes for 2025 by an estimated $129 billion.
4 min read
Explore the IRS inflation-adjusted 2026 tax brackets, for which taxpayers will file tax returns in early 2027.
5 min read