Skip to content

Business Tax Expenditures, Credits, and Deductions

All Related Articles

Corporate tax reform analysis including corporate tax hike economic growth impact

Three Facts Straightening Out the Debate Over Bonus Depreciation

Expensing for capital investment is not a special tax break. Expensing aligns the timing of tax deductions with the timing of actual capital expenditures so that the tax code does not discourage marginal investment projects. 

7 min read
Canada Full Expensing Made Permanent, Capital Investment and Cost Recovery

Full Expensing to Be Made Permanent in Canada

On September 15th, Canada announced that full expensing for machinery, equipment, and patent rights will be made permanent and broadened from around 15 percent to two thirds of business capital investment.

6 min read
Trump tariffs currency appreciation and Trump tariffs value of US dollar impact

Four Ways US Bond Markets Affect Tax Revenue

Federal government debt is over $32 trillion, around the size of the nation’s annual economic output (its gross domestic product, or GDP). Debt levels this high mean US borrowing costs are sensitive to interest rate changes that may otherwise seem small.

5 min read
The Options Guide Shows a Better Way to Fund Social Security

The Options Guide Shows a Better Way to Fund Social Security

While uncapping the payroll tax and raising individual income tax rates are often the go-to reform options for policymakers, base broadeners like ESI and other fringe benefits are much better alternatives. They can raise significant revenue, while improving the neutrality of the tax code and preventing the need for increases in statutory tax rates.

6 min read
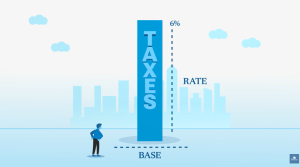
The differene between tax rate vs tax base explainer video

Tax Rate vs. Tax Base

When thinking about taxes, we often consider the tax rate—or what percentage of something is taxed. But there is another factor in considering taxes: the tax base.

The Five Most Pro-Growth Options in the Options Guide

Some taxes have more powerful economic effects than others, and that’s a lesson policymakers should absorb as they work to craft a tax code that encourages growth and raises sustainable revenue.

8 min read
Foreign Research and Development, OBBBA Full Expensing

The Hidden Costs of Foreign R&D Amortization

Foreign R&D generally complements domestic innovation rather than substituting for it, so penalizing foreign R&D weakens US firms in cross-border mergers and acquisitions and in domestic production that depends on global scale.

7 min read

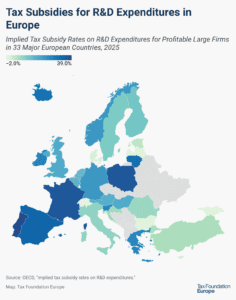
Tax Subsidies for R&D Expenditures in Europe, 2026

Many countries incentivize business investment in research and development (R&D), intending to foster innovation. A common approach is to provide direct government funding for R&D activity. However, a significant number of jurisdictions also offer R&D tax incentives.

5 min read
Can Tax Hikes on the Rich Solve the US National Debt Crisis? Social Security Medicare Spending Entitlement Reform

Can Tax Reform Solve the Debt Problem—or Just Slow It?

This study simulates several large tax increases and consistently finds that even tax increases large enough to close the primary deficit in the near term will lose ground over time and fail to put the debt on a sustainable course. 

41 min read