Spain’s Tax Competitiveness Has Declined Since 2018
Under Spain’s current Social Democratic government, the country has fallen from 27th to 35th (out of 38 OECD countries) in the International Tax Competitiveness Index.
8 min read
Under Spain’s current Social Democratic government, the country has fallen from 27th to 35th (out of 38 OECD countries) in the International Tax Competitiveness Index.
8 min read
As scrutiny over data center investment and AI rises, some commentators are concerned about how expensing interacts with these ongoing investments. Most of these concerns misunderstand what expensing does.
5 min read
Hall’s research helped economists understand how taxes distort investment decisions, while his work with Rabushka shows how to minimize those distortions. Although the US remains far from a pure consumption tax, Hall’s work informs efforts to reduce the tax burden on investment, improve neutrality, and promote long-run economic growth.
3 min read
While there are many factors that affect a country’s economic performance, taxes play an important role. A well-structured tax code is easy for taxpayers to comply with and can promote economic development while raising sufficient revenue for a government’s priorities.
72 min read
Expensing for capital investment is not a special tax break. Expensing aligns the timing of tax deductions with the timing of actual capital expenditures so that the tax code does not discourage marginal investment projects.
7 min read
Poland has one of the most restrictive approaches to the tax treatment of losses in the OECD. Loss carryover provisions allow businesses to deduct their losses in one year against taxable income in another, smoothing their taxable income over time. Their absence or restriction leads to firms with more variable profits and losses over time being taxed at higher rates, penalizing risky investment, such as research and development (R&D), and business expansion.
16 min read
US policymakers have put forward two new tax proposals to address concerns about how artificial intelligence (AI) will impact land, energy, and the workforce.
7 min read
The OBBBA made substantial improvements to cost recovery, but more opportunities remain for policymakers looking to improve the investment climate in the US.
48 min read
The EU Tax Omnibus proposal would create an EU-wide minimum standard for full expensing, but it confines that standard to qualifying tangible assets used in research and development (R&D) rather than to broader asset classes.
16 min read
The Tax Foundation uses and maintains a General Equilibrium Model, known as our Taxes and Growth (TAG) Model to simulate the effects of government tax and spending policies on the economy and on government revenues and budgets.
9 min read
Foreign R&D generally complements domestic innovation rather than substituting for it, so penalizing foreign R&D weakens US firms in cross-border mergers and acquisitions and in domestic production that depends on global scale.
7 min read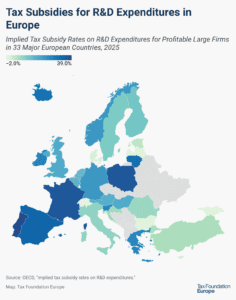
Many countries incentivize business investment in research and development (R&D), intending to foster innovation. A common approach is to provide direct government funding for R&D activity. However, a significant number of jurisdictions also offer R&D tax incentives.
5 min read
The European Commission’s new Tax Omnibus proposal marks a notable step towards improving the simplicity and competitiveness of the EU Single Market.
8 min read
Policymakers should broaden and make permanent full expensing for additional asset classes and pursue structural reforms that reduce distortions in how businesses are taxed. A more consistent and predictable policy environment, paired with targeted improvements to loss treatment, R&D incentives, and compliance burdens, would give small business owners greater confidence to invest, hire, and grow.

The evidence overall paints a far different picture than American Compass presents, and a consistent theoretical framework undercuts its assertions of how tariffs should be expected to impact the economy moving forward.
25 min read
The OBBBA significantly boosted economic prospects by improving the treatment of investment. By making key expensing provisions permanent, the OBBBA created better conditions for long-term growth. However, there’s still work to be done, and the OBBBA provided a blueprint for policymakers to follow.
4 min read
Notably, the OBBBA makes permanent the individual tax changes first put in place by the TCJA, which avoids a tax hike on an estimated 62 percent of tax filers in 2026.
4 min read
Near-term corporate tax payments may fall, and financial statement data may appear unusual, but over time, revenues will stabilize, book-tax gaps will fade, and the US tax code will incentivize domestic investment.
8 min read
Our analysis of the major tax provisions included in the OBBBA finds it will increase long-run GDP by 0.7 percent. The major tax provisions will reduce federal tax revenue by nearly $5.2 trillion between 2025 and 2034, on a conventional basis.
12 min read
As European countries have undertaken a series of tax reforms designed for budgetary stability, policymakers should focus on consumption taxes by making them more neutral and efficient.
15 min read