Pillar Two Implementation in Europe, 2026
22 of the 27 EU Member States have implemented both the income inclusion rule and the qualified domestic minimum top-up tax in 2026.
4 min read
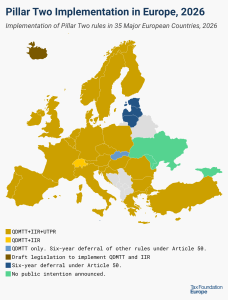
22 of the 27 EU Member States have implemented both the income inclusion rule and the qualified domestic minimum top-up tax in 2026.
4 min read
While the government will never close the tax gap or fully eliminate tax fraud, lawmakers and the IRS can institute several reforms to reduce the gap, including simplifying the tax code, increasing third-party information reporting, and coordinating anti-fraud efforts.
7 min read
While there are many factors that affect a country’s economic performance, taxes play an important role. A well-structured tax code is easy for taxpayers to comply with and can promote economic development while raising sufficient revenue for a government’s priorities.
72 min read
Congress has passed some major simplifying reforms in recent years, but the tax code has still grown more complex over the past few decades. New carveouts, savings vehicles, and targeted tax increases would complicate it further.
8 min read
Americans will spend 6.9 billion hours complying with IRS tax filing and reporting requirements in 2026, costing about $387 billion in lost productivity. Including an additional $157 billion in out-of-pocket costs, complying with the federal tax code will cost Americans more than $544 billion this year, over 1.7 percent of GDP.
10 min read
Many states levy taxes on liquids on a per-barrel basis. However, some states define a “barrel” differently than the standard measurement. The landscape of unharmonious units creates complexity and compliance costs for businesses that must pay these taxes in multiple states.
5 min read
Investment in digital assets, long thought of as a niche interest reserved for enthusiasts, has broken into the mainstream. In 2026, about one in five US adults report being invested in or using cryptocurrency.
5 min read
Ten years ago, then-Speaker Paul Ryan and Ways and Means Chairman Kevin Brady released the “Better Way” Tax Plan, the blueprint that would eventually become the Tax Cuts and Jobs Act of 2017—the largest overhaul of the US tax code in over 30 years.
A new paper finds that foreign exporters absorbed 47 percent of the tariff burden, passing on a smaller share to US importers than estimated by other studies.
6 min read
If America’s leaders today want to learn how to build a lasting system on the foundation of simplicity and neutrality, they should follow the Siim Kallas blueprint.
4 min read
The Belgian proposal departs significantly from sound tax policy principles and risks generating substantial economic distortions, legal uncertainty, and trade frictions while raising relatively little revenue.
In 2025, the CTP reduced the backlog of premarket tobacco product applications (PMTAs) by about 70 percent. This year, the CTP is already accelerating PMTA reviews further and allowing some leeway for products under review but not yet officially authorized. This is great progress, but much more can be made.
7 min read
Poland has one of the most restrictive approaches to the tax treatment of losses in the OECD. Loss carryover provisions allow businesses to deduct their losses in one year against taxable income in another, smoothing their taxable income over time. Their absence or restriction leads to firms with more variable profits and losses over time being taxed at higher rates, penalizing risky investment, such as research and development (R&D), and business expansion.
16 min read
In June, the Dominican Republic rushed through a package of tax legislation in seven days. International examples demonstrate that consultation, transparency, and clarity are key factors for successful tax reform.
5 min read
If Canada doesn’t make these provisions permanent, it will drop to 12th place in the capital cost recovery ranking once provisions expire in 2034.
5 min read
Poland taxes its individual business owners through alternative regimes and a series of thresholds, several of them sharp notches that imply significant tax costs for businesses crossing them.
11 min read
The OBBBA made substantial improvements to cost recovery, but more opportunities remain for policymakers looking to improve the investment climate in the US.
48 min read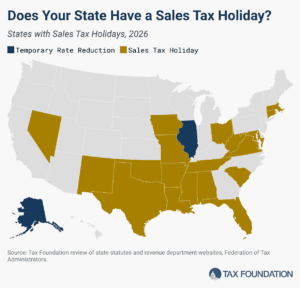
However well-intended they may be, sales tax holidays remain the same as they always have been—ineffective and inefficient.
12 min read
The EU public country-by-country data provides information on taxes and profits that do not align with standard financial disclosure requirements.
6 min read
Because withholding taxes can create double taxation and administrative friction even where foreign tax credits are available, the European Commission’s 2026 Tax Omnibus proposal to eliminate them on dividend, interest, and royalty payments between EU companies regardless of holding percentage would foster stronger cross-border savings and investment.
6 min read