Maine outperforms many of its Northeastern peers but nevertheless performs below average on the Index, with the property tax and corporate income tax being its least competitive tax types.
Maine’s property tax structure is among the least competitive in the nation due to high rates, its levying of both an estate tax and a real estate transfer tax, and its taxation of tangible personal property without a de minimis exemption. However, Maine’s high property taxes come as a trade-off for its lack of local sales taxes, which enables the state to maintain one of the lowest combined sales tax rates in the nation.
Maine includes global intangible low-taxed income (GILTI) in its corporate tax base, which will transition to a tax on net CFC-tested income (NCTI) when the state updates its conformity statute. Maine’s throwback rule raises the tax burden Maine-based businesses face when they sell tangible property into states with which they do not have nexus. Additionally, Maine’s lack of first-year expensing for C corporations discourages in-state investment, although its conformity to the Section 179 expensing allowance makes its treatment of small business investments more competitive than some of its peers.
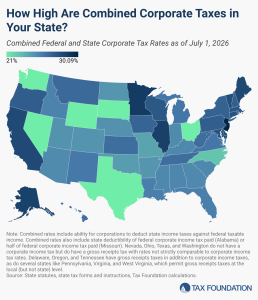
Corporations in the United States pay federal corporate income taxes levied at a 21 percent rate. Forty-four states and D.C. also levy taxes on corporate income, with top marginal rates ranging from 2.5 percent in North Carolina to 11.5 percent in New Jersey.
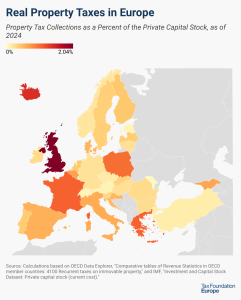
High property taxes levied not only on land but also on buildings and structures can discourage investment in infrastructure, which businesses would have to pay additional tax on.
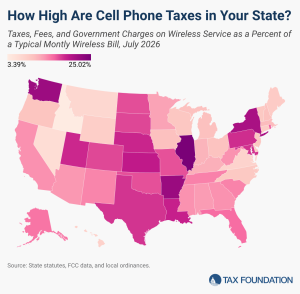
Applying the sales tax, a traditional broad-based consumption tax, is perfectly appropriate, but excessive targeted taxation of wireless services lacks the traditional justifications—a user-pays system or the internalization of social costs—for excise taxation, raising consumer costs and discouraging investment.